MediaMarktSaturn under Chinese control: 2.2 billion euros for Europe's electronics retailer – How JD.com could change the electronics trade – Creative image on the topic, with AI: Xpert.Digital
MediaMarkt and Saturn will remain – but who will control the business behind them in the future?
JD.com and Ceconomy: Why the takeover is far more than a change of ownership
Europe's electronics retail sector is facing upheaval: What the JD.com takeover means
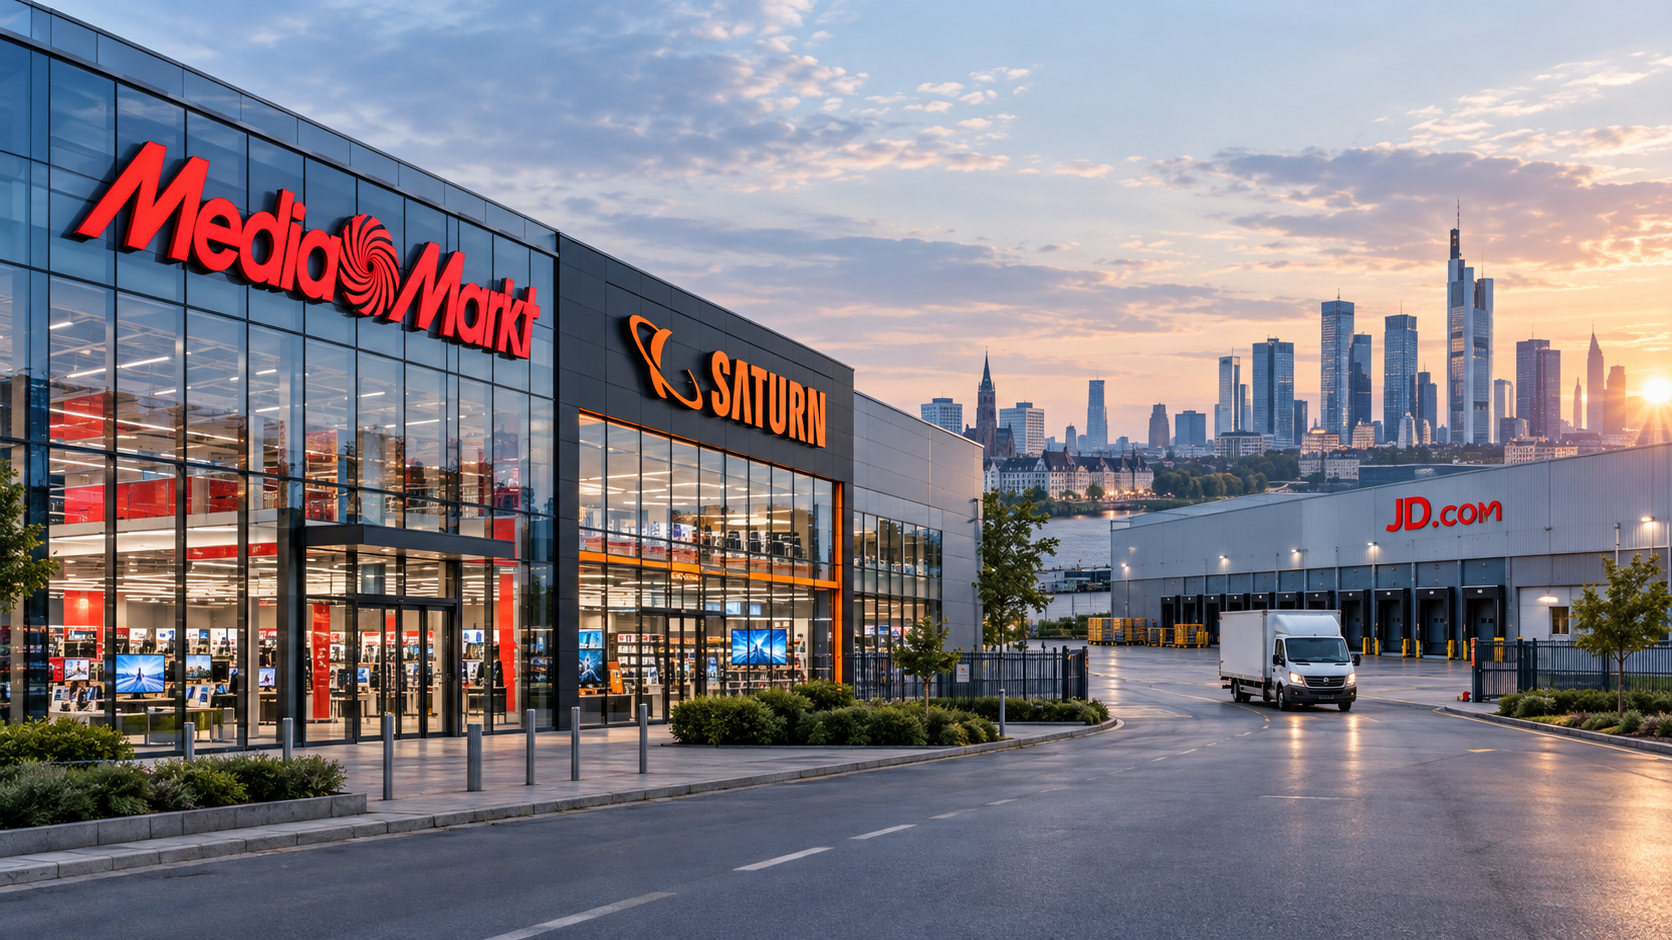
The European Commission has conditionally approved the takeover of Ceconomy, the parent company of MediaMarkt and Saturn, by the Chinese retail and technology group JD.com. This fulfills a key prerequisite for the change of ownership. Formal completion is still pending on November 3, 2026; according to the companies involved, it is expected to take place in the coming days. JD.com aims to finalize the deal by November 12. The takeover bid values Ceconomy's equity at approximately €2.2 billion. This represents a European retail business with more than 1,000 stores in eleven countries and most recently generated annual sales of around €24 billion.
But the crucial question isn't whether a different name will appear above the entrances of electronics stores in the future. It's about who controls financing, the flow of goods, technical systems, and access to customers. JD.com could strengthen Ceconomy with its logistics, technology, and greater purchasing power. At the same time, the change of ownership raises questions about competition, government subsidies, customer data, and Europe's economic dependence.
The acquisition opens up opportunities for more efficient supply chains, better integrated stores and online shops, and new investments. Whether this will result in sustained improvements in performance, however, remains to be seen. EU approval is no guarantee of success: it is subject to conditions designed to limit potential distortions of competition. The crucial factor will be whether JD.com can leverage the strengths of its European retail network without weakening local market knowledge and fair competition.
Europe's trademarks will remain – but who will control the business behind them in the future?
The European Commission has conditionally approved the takeover of Ceconomy, the parent company of MediaMarkt and Saturn, by the Chinese retail and technology group JD.com. This fulfills a key prerequisite for a change of ownership whose economic significance extends far beyond the sale of two well-known retail brands. Formal completion is still pending on November 3, 2026; according to the companies involved, it is expected to take place in the coming days. JD.com aims to finalize the deal by November 12. The takeover bid values Ceconomy's equity at approximately €2.2 billion. This is compared to a European retail business with more than 1,000 stores in eleven countries and most recently, annual sales of around €24 billion.
The crucial question, therefore, is not whether a different name will appear above the entrances of electronics stores in the future. Far more important is who controls the financing, the flow of goods, the technological systems, and access to customers. It is precisely at this point that the strategic interests of a Chinese corporation clash with the economic interests of Europe.
The merger offers understandable opportunities: more efficient supply chains, better integration of brick-and-mortar stores and online business, additional investments, and more efficient processes. At the same time, risks arise from growing dependencies, potential distortions of competition, and a shift in economic decision-making power. A convincing assessment must distinguish between these two aspects: an investor's origin does not automatically determine the quality of an acquisition. Conversely, regulatory approval does not automatically transform a strategically sensitive change of ownership into a guaranteed economic success.
Behind the well-known brands lies a European distribution network of considerable value
Ceconomy is not simply a collection of large retail spaces. The group combines brand recognition, customer relationships, procurement volume, supplier contacts, service capacities, and a presence built up over years in various European markets. The more than 1,000 locations, together with the online business, form an infrastructure that a new competitor could hardly replicate on its own in the short term. Around 400 stores are located in Germany.
This represents a significant strategic advantage for JD.com. Anyone entering a new market solely through an online shop must first gain attention, build trust, understand customer habits, and establish a reliable delivery and service organization. Acquiring a well-known retailer shortens this process. While it doesn't automatically guarantee the buyer financial success, it does provide access to an already functioning market.
Branches fulfill several functions simultaneously. They serve for sales, customer service, order collection, returns, and brand visibility. For products requiring extensive consultation or that are bulky, a local presence can be particularly important. A refrigerator, a washing machine, or a high-end television has different requirements for delivery, installation, and warranty processing than a small item that can be easily shipped.
However, the value of a branch network depends on how well these functions are integrated. A large sales area is not an advantage in itself. It only becomes a strategic asset when it attracts sufficient demand, enables additional services, and can be operated at reasonable costs.
This is precisely where the economic duality of the business lies: What represents a network that is difficult to copy for a high-performing operator can become a costly asset for a poorly organized operator.
Why €24 billion in revenue doesn't justify a purchase price of €24 billion
The ratio between revenue and acquisition valuation seems striking at first glance. An equity valuation of approximately €2.2 billion contrasts with annual revenue of roughly €24 billion. This equates to a valuation of approximately nine percent of annual revenue. This ratio might give the impression of a particularly favorable purchase. However, it is unsuitable as the sole valuation criterion.
Revenue initially describes the total volume of business processed. It doesn't yet tell you how much of that remains after expenses like purchasing goods, personnel, rent, logistics, IT, depreciation, interest, and taxes. Especially in retail, a company can generate very high revenues and yet retain only a small portion as profit.
The latest preliminary financial figures illustrate this scale. With sales of around €24 billion, Ceconomy achieved adjusted earnings before interest and taxes (EBIT) of €515 million. This corresponds to an adjusted operating margin of approximately 2.1 percent. According to the company, this result represents a 27 percent increase compared to the previous year. This development demonstrates improved profitability, but also a still relatively narrow profit margin.
Even small changes in the cost or revenue structure can therefore have significant effects. An improvement in the operating margin of half a percentage point would, with unchanged revenue, theoretically correspond to approximately €120 million in additional annual operating profit. Conversely, a similarly large deterioration could consume a considerable portion of profit. This is a sensitivity analysis, not a forecast.
Furthermore, the equity valuation should not be equated with the total economic value of the company. Financial liabilities, liquid assets, lease obligations, and other balance sheet items influence the actual burden on a buyer. Simply dividing the offer price by revenue overlooks both the capital structure and the investment requirements.
For JD.com, the acquisition could still be attractive. The strategic benefits of a European distribution network could exceed current profits. However, this additional value must first be realized through improved processes, increased customer loyalty, or new revenue streams.
Ceconomy will not be taken over from a standstill
The transaction should not be portrayed as a simple story of a struggling European retailer being rescued by a financially powerful foreign buyer. Rather, the available financial figures reveal a company that had already expanded its profitability and digital activities prior to the change of ownership.
In fiscal year 2024/25, Ceconomy generated revenue of €23.1 billion and an adjusted operating profit of €378 million. In the previous year, this figure was €305 million. Online sales reached approximately €5.7 billion; the reported online share was 26 percent. The business with services and complementary solutions accounted for roughly €1.4 billion in revenue.
These figures are important for context for two reasons. First, JD.com is not acquiring a completely undeveloped digital business. A significant part of the transformation has already begun. Second, the new owner must demonstrate that its contribution goes beyond what Ceconomy could have achieved on its own.
The subsequently reported preliminary figures of approximately €24 billion in revenue and €515 million in adjusted operating profit indicate a further improvement. However, these should not be equated with a final audited annual report. For a reliable assessment, the development of free cash flow, investments, and capital employed remain particularly relevant.
A rising adjusted profit is positive, but it's not the same as readily available cash. A retailer can improve their results while simultaneously needing more capital for inventory, technological upgrades, or store renovations. Therefore, the economic success of the ownership change will not only be reflected in the profit and loss statement, but also in how much cash the business model actually generates after necessary investments.
JD.com is buying faster access to Europe
From JD.com's perspective, the acquisition primarily accelerates its access to the European market. The company describes itself as a technology- and supply chain-oriented provider, combining retail activities with logistics and technology services. The strategic agreement with Ceconomy aims to support its development into a leading European platform for omnichannel electronics retail.
The economic connection is plausible: JD.com can contribute technological and logistical capabilities, while Ceconomy provides local presence and existing customer relationships. The buyer thus gains not only additional sales revenue but also a potential application for its infrastructure.
Such a merger can more closely link several stages of the value chain. Information about demand can improve procurement. More precise inventory management can reduce storage costs and stockouts. More reliable deliveries can increase customer satisfaction. A better service offering, in turn, can create additional purchase incentives.
However, this chain of cause and effect is no guarantee. European countries differ in terms of language, purchasing behavior, work organization, data protection requirements, and competitive structure. A technology that is successfully used in one market cannot be transferred to other markets without adaptation.
The real challenge of integration, therefore, lies not in replacing existing systems with a uniform model as quickly as possible. The crucial factor is combining the strengths of both sides in such a way that local market knowledge is preserved and technical improvements are truly implemented in everyday practice. Excessive centralization could weaken precisely the customer proximity that makes an acquisition attractive.
The most significant efficiency gain lies between the warehouse and the front door
In the electronics retail sector, competition is often perceived through sales prices. However, a significant part of economic performance is generated behind the scenes: in order forecasting, inventory turnover, product availability, transport planning, and returns processing.
A retailer who orders too much stock ties up capital and risks write-offs or price reductions. If they order too little, they lose revenue and disappoint customers. Managing inventory is particularly difficult with products whose appeal can decline rapidly due to new model generations.
Herein lies a potential benefit of additional technological capabilities. More precise demand forecasts could help to better distribute products across warehouses and markets. Closer coordination between online sales and brick-and-mortar stores could reduce unnecessary parallel inventory. Existing market stock could be used for certain orders, provided the additional processing and transportation costs justify it.
However, such a model shouldn't be judged solely on speed. Extremely fast delivery is of little economic value if it consistently costs more than the customer pays for it or offsets through additional purchases. Processing an online order from a branch also incurs personnel costs, packaging expenses, and organizational complexity.
The relevant benchmark is therefore the total contribution of an order to the overall result. This includes not only the sales price and purchase costs, but also payment processing, delivery, returns, warranties, and customer service. A viable integration improves this overall contribution, rather than simply producing impressive delivery times.
Why Brussels examines not only market shares, but also the origin of economic advantages
The European approval addresses a particularly sensitive issue: competition can be distorted not only by company size, but also by state-sponsored financing and infrastructure.
The Commission found that JD.com had received Chinese subsidies in the form of preferential financing, tax breaks, and grants. It saw a risk that the resulting logistical and technological capabilities could also benefit Ceconomy after the acquisition and strengthen their combined ability to engage in aggressive pricing.
Economically, this concerns the origin of a cost advantage. If a company operates more efficiently, develops better technologies, or understands its customers more precisely, the resulting competitive advantage is fundamentally part of the market economy's performance process. Problems arise when this same advantage is based on government subsidies that are not available to other market participants and distort competition.
A distinction must be made between favorable prices and unfair competition. A low price, in itself, is not proof of distortion. It can result from efficient procurement, lower administrative costs, or a different business model. The crucial question is whether economic advantages are enabled by public support and how these advantages affect the European market.
The review also shows that the relevant competitive area does not end at national borders. An advantage gained in a third country can be transferred to European subsidiaries via intra-group financing, services, or technologies. Control must therefore extend beyond the individual sales company.
Ten years of market conditions are intended to separate government benefits from operational business
The agreed conditions address several aspects of this potential transfer. Transactions between JD.com and Ceconomy must be conducted on market terms. This explicitly includes financing. Furthermore, JD.com must offer warehousing, logistics, and technology services to other companies under the same conditions as Ceconomy. These commitments are valid for ten years; an independent trustee will monitor their implementation under the supervision of the Commission.
This does not prohibit the merger, but rather provides it with an economic protection mechanism. Ceconomy is allowed to benefit from the services of the new owner. However, the advantage should not arise from artificially favorable prices or financing conditions being granted within the group that remain unavailable to competitors.
The additional opening of services to third parties is particularly noteworthy. It could prevent state-sponsored capabilities from exclusively benefiting a single corporate trading platform. In the best-case scenario, this would also create access to high-performance infrastructure for other traders.
However, practical implementation is challenging. Market-standard terms are easier to compare for a standard loan than for a custom-developed software solution or a complex logistics package. Price alone is not always sufficient for a comparison. The scope of services, service quality, contract duration, liability distribution, and technical connectivity options also influence the economic value.
Therefore, the effectiveness of the requirements will depend on their implementation. A formally identical price would be of little significance if external customers experienced longer delivery times, limited functionality, or significantly higher integration costs. The crucial question is whether comparable services are actually available under comparable conditions.
Our EU and German expertise in business development, sales and marketing


Our EU and German expertise in business development, sales and marketing - Image: Xpert.Digital
Industry focus areas: B2B, digitalization (from AI to XR), mechanical engineering, logistics, renewable energies and industry
More information here:
A thematic hub offering insights and expertise:
- Knowledge platform covering global and regional economies, innovation and industry-specific trends
- A collection of analyses, insights, and background information from our key areas of focus
- A place for expertise and information on current developments in business and technology
- A hub for companies seeking information on markets, digitalization, and industry innovations
The importance of customer data in the competition among electronics markets
The difficult line between desirable synergy and prohibited cross-subsidization
A fundamental conflict of objectives remains: acquisitions are often intended to take place precisely because the merger of two companies creates advantages. At the same time, regulations are meant to prevent certain advantages from being passed on in a way that distorts competition.
Not every improvement within a company is cross-subsidization. If joint planning reduces duplication of effort or a better IT system demonstrably lowers costs, this can result in legitimate efficiency gains. Likewise, not every low service price is necessarily unreasonable. A large customer may receive better terms due to volume, predictability, or lower processing costs.
It would be problematic, however, if losses or artificially low transfer prices were used to covertly pass on government benefits to Ceconomy. The economic review must therefore understand why a price is determined and whether the underlying assumptions would also hold true between independent companies.
For the company itself, the regulations create additional requirements for transparency and documentation. Financing, logistics, and technology must be organized in such a way that their conditions remain verifiable. This separation can incur costs and limit individual synergies.
However, this is not necessarily a disadvantage for the overall project. Clear billing systems can also make it internally visible which services are actually profitable. A business model that only appears profitable due to difficult-to-understand discounts is less sustainable in the long run than one whose advantages are verifiable under market conditions.
Customers could benefit, but not every price reduction is permanent
For consumers, the crucial question is whether the change of ownership improves the specific offerings. Potential benefits include greater product availability, more reliable deliveries, improved digital processes, and more integrated services. Lower prices are also possible, provided that efficiency gains are actually passed on to customers.
Whether this happens depends on competition and corporate strategy. Cost reductions can be used for price reductions, but also for higher profits, additional investments, or the expansion into new business areas. Therefore, a more efficient supply chain does not automatically lead to a lower final price.
Furthermore, there is the time perspective to consider. Attractive offers in the short term can stimulate competition. However, little would be gained in the long run if, at the same time, the number of high-performing alternatives were to decline sharply and customer dependence on a few large providers were to increase. This possibility is not a proven outcome of the acquisition, but rather a risk that should be taken into account when evaluating large trading platforms.
Especially in the electronics trade, simply looking at the device price isn't enough. Delivery, setup, financing, insurance, extended warranties, and repairs can significantly alter the overall cost. Therefore, a low starting price doesn't necessarily mean the best overall deal.
A compelling consumer experience would combine several elements: competitive prices, transparent additional services, reliable accessibility, and efficient problem resolution. The success of a trading platform is evident not only at the moment of purchase but also afterwards.
For competitors, the acquisition could lead to a productivity shock
Other retailers must prepare for a potentially more powerful competitor. This affects not only large electronics chains, but also regional suppliers and specialized online shops.
If Ceconomy improves its logistics, inventory management, and digital processes, its existing weaknesses will no longer serve as points of attack. Competitors would then have to rely more heavily on special product ranges, consulting services, service quality, or a clearly defined customer base to win them over.
For smaller companies, this is a double-edged sword. Increased competition can create economic pressure, but it can also open up new opportunities. The promised opening of JD.com services could, under suitable conditions, provide access to technologies or logistics services that an individual retailer could not develop economically on their own. The requirement that these services be offered on a level playing field is part of European obligations. Whether this will result in practically usable offerings remains to be seen.
A new dependency must not be overlooked. When a retailer outsources key processes to a service provider that is also affiliated with a competitor, contract design, data access, and switching options become particularly important.
From a macroeconomic perspective, the most favorable development would be a productivity boost across multiple providers. A less advantageous situation would be one in which the efficiency of a single corporation increases, but independent competitiveness is lost elsewhere. Therefore, the actual openness of the infrastructure is just as economically significant as its technical performance.
Services can become more important than selling the next television
The revenue model for electronics retailers is changing when they no longer earn money solely from the difference between the purchase and selling price. Complementary services can extend customer relationships and generate additional revenue.
Ceconomy already has such a business. In the 2024/25 financial year, the Services and Solutions division generated approximately €1.4 billion in revenue, representing a 12.5 percent increase on a like-for-like basis, according to the company. This includes various services related to the purchase and use of devices.
From an economic perspective, this development is understandable. A single device is often offered by multiple retailers and is therefore easy to compare. Consultation, installation, repair, and technical support are more closely tied to specific customer needs. This can reduce the interchangeability of a retailer.
However, this business model is not an automatic profit driver. Services require qualified employees, effective scheduling, quality control, and reliable partners. Poor execution can damage a brand's reputation more than a late standard delivery.
Transparency is also crucial for insurance, financing, and warranty products. Additional revenue does not automatically translate into additional customer benefits. A sustainably successful business model must offer services whose price and benefits are transparent and comprehensible.
For JD.com and Ceconomy, the combination of physical presence and digital management could be particularly interesting. The store then serves not only as a sales location but also as a touchpoint for building a longer-term customer relationship. Whether this results in genuine differentiation depends on the quality of execution.
A retailer can become a platform – with new conflicts of interest
The strategic development towards a trading platform expands the business model. A company can not only sell its own goods, but also integrate external suppliers, additional services, and digital intermediary services. Ceconomy and JD.com have explicitly stated the further development of their omnichannel platform business as a goal.
The economic appeal lies in the fact that growth doesn't always have to be financed through additional inventory. Integrating third-party offerings can generate additional revenue without the platform operator assuming the entire inventory risk. At the same time, the selection for customers increases.
However, this development also changes responsibilities. Customers need to be able to identify their contractual partner, who is responsible for delivery, and who handles any defects. A well-known brand can inspire trust across the entire platform, even if some of the operational services are provided by third parties.
Conflicts of interest also arise within the ecosystem. The platform operator can simultaneously act as a retailer, technical service provider, and rule-maker. They may decide which offers are visible and how different providers gain access to customers.
For long-term competitiveness, the size of the product range is therefore not the only decisive factor. Fair access conditions, transparent rules, and a clear separation of roles are equally important. A platform creates additional economic value when it facilitates transactions and reduces search costs. It becomes more problematic when its position is primarily used to increase dependencies.
Employees are caught between investment opportunities and pressure to rationalize
Ceconomy is a major employer. For 2024, it projected around 50,000 employees worldwide, nearly 20,000 of whom were in Germany. The original investment agreement included commitments regarding employees, locations, and brands, as well as the intention to continue Ceconomy as an independent European business with its own independent technical architecture.
Such commitments are important, but should not be mistaken for a permanent immutability of the company. Even if an acquisition does not trigger immediate job cuts, digitalization and new business models are changing the demands placed on the workforce.
Automated inventory management can reduce manual tasks. At the same time, it can create additional responsibilities in technical consulting, repairs, data analysis, or omnichannel customer service. Whether employees benefit from this depends largely on further training and work organization.
The distribution of productivity gains is also open to debate. Improved processes can ease the burden of daily work and create economic flexibility. However, they can also be associated with increased performance pressure and stricter regulations.
Therefore, a reliable assessment should not only consider employee numbers. Qualification development, working conditions, co-determination, and whether operational decisions continue to be made sufficiently close to European markets are also relevant.
A well-managed change of ownership could strengthen existing expertise. Conversely, a poorly implemented integration could result in a loss of know-how that cannot be replaced quickly by new software.
Customer data is both an economic asset and a trust risk
The German approval of the change of ownership was subject to conditions for the protection of personal customer data. According to published information, the German government also has extensive monitoring and control rights, as well as the power to revoke the approval in the event of violations.
The issue extends beyond legal obligations. Customer data can improve demand forecasts, refine marketing, and support service processes. That's precisely why it's crucial to understand which data is processed, who has access to it, and for what purposes it may be used.
It would be wrong to assume that a foreign owner necessarily leads to unauthorized data transfers. Likewise, a formal commitment alone is insufficient to eliminate all risks. Crucial factors are the technical architecture, access rights, control mechanisms, and verifiable operational processes.
The announced independent European IT structure can play an important role in this context. However, it must be compatible with the desired use of additional technology. The more systems are integrated, the more precisely data flows and responsibilities must be regulated.
For the company itself, data protection is also a matter of economic trust. A retailer can invest in their brand for years and lose considerable credibility through a single serious incident. Therefore, an effective data strategy should not simply collect as much information as possible, but rather combine clear business benefits with reliable limitations.
Europe's openness to investment is becoming more politically challenging
The change of ownership touches upon a fundamental area of tension within Europe. Foreign capital can promote investment, technological exchange, and competition. At the same time, dependencies can arise if important distribution channels, data structures, or technical capabilities are increasingly controlled outside of Europe.
In this case, a political dimension came into play: China responded to the European investigation with threats of countermeasures. This transformed a company-related review into a conflict over the scope of economic control and state influence. However, the decision cannot be meaningfully reduced to a simple power struggle between Europe and China.
Approval subject to conditions represents a middle ground. Market access remains open in principle, while certain forms of benefit transfer are to be limited. This is more economically demanding than a blanket ban and less politically convenient than unconditional approval.
This presents Europe with a further challenge. Competition oversight can limit distortions, but it cannot replace domestic technological capabilities. If European trading companies remain permanently dependent on external expertise in software, logistics, or financing, this weakness cannot be remedied solely through regulation.
The long-term answer must therefore also lie in better investment conditions, efficient infrastructure, and competitive companies. Strategic independence does not arise from fending off every foreign investor, but from European actors having attractive alternatives and their own room for maneuver.
Three development paths show how success will be measured
Three plausible development paths can be distinguished for the coming years. These are not predictions, but rather help to highlight the decisive influencing factors.
In the best-case scenario, a productive partnership is achieved. Ceconomy improves product availability, inventory management, and digital processes without losing its local market expertise. Services are expanded, the operating margin increases due to internal performance, and European regulations are effectively implemented. Customers benefit from improved overall service, and employees from a more stable economic outlook.
In a medium-term scenario, improvements remain limited. Technological modernization and better procurement primarily offset rising costs and intense competition. The company grows or stabilizes without achieving a fundamental leap in productivity. In this case, a change of ownership would be neither an economic breakthrough nor a failure.
In a worst-case scenario, integration and control are underestimated. More complex systems, cultural friction, or unclear responsibilities could increase costs. At the same time, conflicts over financing, data access, or compliance with regulations could generate additional expenses. Increased dependence on internal services would then not be offset by corresponding productivity gains.
Which path is more likely cannot be deduced from the purchase price or the investor's origin. Operational decisions are decisive. The development of free cash flow, inventory turnover, service quality, and the actual return on additional capital invested will be particularly telling.
The economic test will come after approval
With European approval, political and regulatory uncertainty has been reduced, but the real economic test is only just beginning. The announced continuation of the business model and strategy should not be interpreted as a promise that everything within the company will remain unchanged. Even the planned use of additional technology and logistics necessitates changes.
The direction of these changes is crucial. If JD.com helps Ceconomy operate with less tied-up capital, better product availability, and more reliable service, then demonstrable economic added value will be created. However, if primarily financial advantages are shifted, dependencies deepened, or market positions expanded at the expense of sustainable competition, the outcome would be significantly more critical.
The European decision establishes a framework, but not a guarantee of success. Ten-year commitments to standard intra-group transactions and the opening up of certain services are intended to prevent state aid from being passed on unchecked into European trade. Their significance lies precisely in allowing legitimate efficiency gains while limiting distorting advantages.
The rationale is therefore neither alarmist nor euphoric: The acquisition offers industrially justifiable opportunities because it can combine an established European distribution network with additional technological and logistical capabilities. At the same time, it remains sensitive from an economic policy perspective because sales, financing, data, and infrastructure will be more closely consolidated under the control of an international corporation.
Whether this will lead to a strengthening of the European electronics retail sector will not be decided by the logos of MediaMarkt and Saturn. It will be decided by whether the new ownership structure delivers measurably better performance that can withstand verifiable competitive conditions.
🎯🎯🎯 Data-driven B2B industry hub as a quasi-in-house solution


The quasi-in-house solution: How Xpert.Digital closes operational gaps in B2B marketing and sales – Smart Content-Driven Business - Image: Xpert.Digital
Xpert.Digital is a data-driven B2B industry hub led by Konrad Wolfenstein . The company acts as an external, quasi-in-house solution for industrial partners, closing operational gaps in marketing, content, and sales – without requiring additional resources on the client side.
More information here:
Your global marketing and business development partner
☑️ Our business language is English or German
☑️ NEW: Correspondence in your native language!

Konrad Wolfenstein
I and my team are happy to be available to you as your personal advisor.
You can contact me by filling out the contact form here wolfenstein@xpert.digital:or simply call me at +49 7348 4088 965. My email address is
I'm looking forward to our joint project.