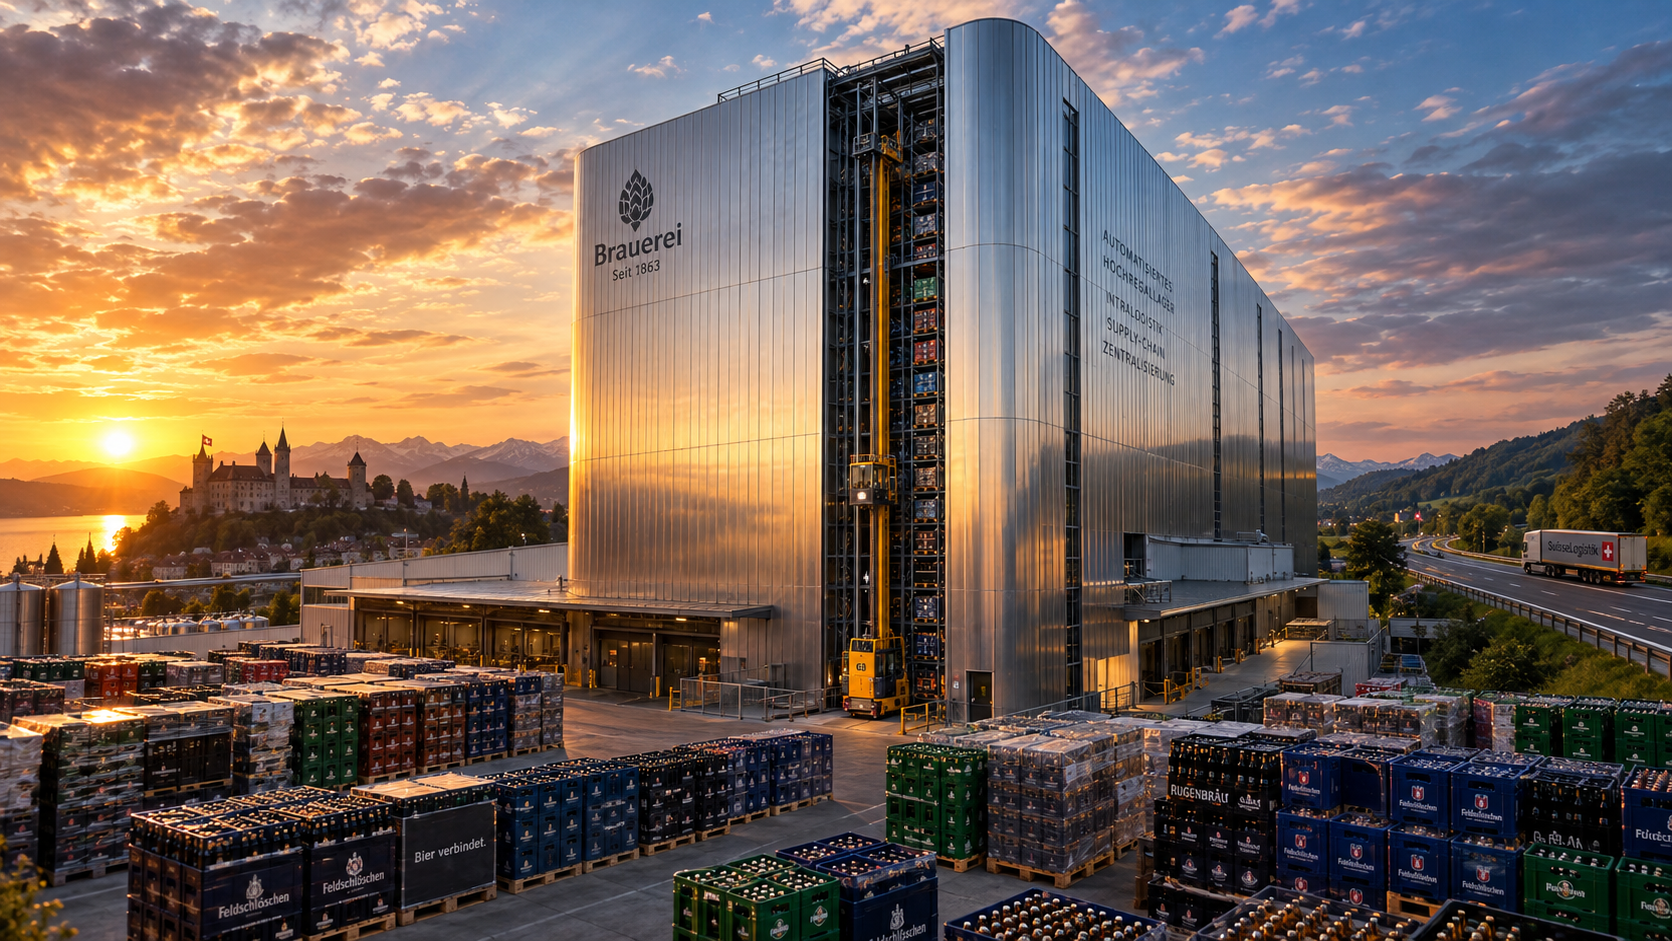
The ingenious logic behind Feldschlösschen's new mega high-bay warehouse: Despite the beer crisis – less beer, more concrete – creative image on the topic, created with AI: Xpert.Digital
50,000 pallets, 30 meters high: The secret of the new mega-project in Rheinfelden
Swiss people drink less beer – why the largest brewery is still building a gigantic structure
Bucking the trend: Why the brewing giant is suddenly pouring tens of millions into reinforced concrete
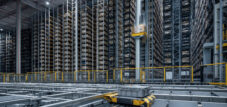
The Swiss beer market has been shrinking for years, but the long-established Feldschlösschen brewery is responding with a superlative construction project. At its headquarters in Rheinfelden, a 30-meter-high, fully automated high-bay warehouse with space for 50,000 pallets is being built for a high double-digit million-franc sum. At first glance, this enormous single investment seems paradoxical in times of declining per capita consumption. But behind the gigantic structure lies a cold, business-like logic: it is not a bet on future growth, but a radical measure to increase efficiency. Through vertical integration, the elimination of expensive external warehouses, and a high degree of automation, the company is responding to scarce building land, increasing cost pressures, and a chronic shortage of skilled workers. Thus, this seemingly contradictory mega-project becomes a groundbreaking lesson in how the consumer goods industry is preparing for the future in saturated markets and defending margins not on the sales shelf, but in the supply chain.
Concrete against beer shortages: Why a shrinking brewery is building a gigantic pallet tower
When sales decline and the company still pours millions into reinforced concrete – the logic behind the Rheinfelden gamble
It's a paradoxical picture at first glance. Beer consumption in Switzerland has been in a structural decline for years; per capita consumption has fallen from seventy liters to around forty-six liters recently, and Feldschlösschen itself had to accept a three percent drop in revenue and a five percent slump in beer sales in 2025. And yet, this very company has decided to make the largest single investment in decades – in a thirty-meter-high high-bay warehouse, the size of a football field, with fifty thousand pallet spaces, for a high double-digit million-franc sum. To understand this apparent contradiction, one must not see the investment as a bet on more beer, but rather as a cold-blooded economic restructuring of the value chain. Therein lies the real story.
A tower for eternity, built in a shrinking market
At its headquarters in Rheinfelden, directly adjacent to the historic castle from which it takes its name and along the motorway, a building will be constructed in the coming years that will alter the existing skyline of the area. The building will be approximately 100 meters long, 75 meters wide, and 30 meters high, extending an additional 5 meters into the ground. These dimensions exceed the previously permitted maximum building height of 20 meters, which is why Feldschlösschen had to undergo a partial zoning plan revision, approved by the Rheinfelden municipal assembly in June 2025. Following the completion of this revision and the submission of the building application in December 2025, construction is scheduled to begin in spring 2026, with completion expected in 2030. In addition to the actual high-bay warehouse, the project includes a new rail loading facility, a monorail pallet conveyor system, and an additional smaller warehouse, with a facade made of curved zinc sheeting.
The key business metric isn't height, but capacity. With the new building, Feldschlösschen is tripling its storage capacity at the site, as the company itself states. This tripling is the lever that renders the entire existing logistics infrastructure obsolete. Currently, the brewery operates three external warehouses around Rheinfelden – in Wallbach, Kaiseraugst, and Läufelfingen – because the capacity of the existing central warehouse has long been exhausted. These three depots can be eliminated with the new high-bay warehouse, and furthermore, other external warehouses scattered across the country can be closed or converted into simple transshipment points. What's being built here is therefore less an additional warehouse and more the replacement of an entire, historically grown, and fragmented network of makeshift solutions.
The real calculation: Why centralization is more effective than growth
The crucial economic point is that this investment pays off even with stagnant or declining sales. A decentralized warehouse network generates structural costs that are largely independent of the sales volume: Each external warehouse incurs rent or tied-up capital, its own personnel and operating costs, duplicate handling processes, and, above all, a constant shuttle service between production and storage facilities. This internal transport is precisely the hidden cost driver of any distributed structure. Feldschlösschen points out that centralization eliminates the corresponding truck transports to the external warehouses. The savings, therefore, do not result from increased sales, but from the elimination of inefficiencies within its own process chain.
This logic is characteristic of capital-intensive consumer goods industries in mature, saturated markets. When volume growth as a source of profit disappears, competition shifts from revenue to cost. Margins are then no longer defended at the checkout, but in the supply chain. In this context, an automated high-bay warehouse is the most effective tool available because it addresses several cost blocks simultaneously: It reduces space requirements through vertical integration, it lowers personnel costs through automation, it shortens internal transport routes, and it consolidates inventory at a single point directly connected to production. The investment is therefore fundamentally an efficiency investment, not a growth investment – and precisely for that reason, so rational in a shrinking market.
Another aspect that is often overlooked in public perception is the capital tied up in inventory itself. Modern warehouse management enables more precise inventory control, lower safety stock levels, and faster turnover times. In the beverage industry, with its seasonal demand peaks, minimum shelf lives, and high pallet volumes, optimizing tied-up working capital directly contributes to free cash flow. A centralized, automated warehouse therefore not only reduces operating costs but also improves balance sheet efficiency.
Vertical instead of horizontal: The economics of scarce land
Why does Feldschlösschen build upwards and not horizontally? The answer lies in the fundamental shift in the relative costs of land compared to structural steel and automation technology. In densely populated Central European economic regions, and Switzerland is an extreme case in this regard, building land has become the scarcest and most expensive production factor in logistics. Strict spatial planning laws, zoning plans, and densification regulations further restrict horizontal expansion. Vertical construction is therefore not an architectural gimmick, but a simple business necessity: A significantly larger number of parking spaces are created on the same footprint.
The relevant market data impressively underpins this logic. Automated densification can increase storage density by around thirty percent, while significantly reducing operating costs per stored pallet. It is precisely this density that makes the seemingly expensive construction more cost-effective in the long run than the alternative of several low-rise warehouses plus external storage areas. The core economic principle can be summarized in a simple relationship: The total cost per pallet space over the life cycle comprises the proportional land costs, construction and facility costs, and ongoing operating costs. Vertical densification drastically reduces the cost of the first block because the same land price is spread across many more pallet spaces.
Industry benchmarks help to put the investment level into perspective. Simple pallet racking systems start at around 75 to 200 US dollars per pallet position, while fully automated systems cost significantly more, with installation and software integration accounting for another 25 to 35 percent of the project costs. Medium-sized, fully automated high-bay warehouses typically range between 5 and 20 million euros, with annual maintenance costs amounting to 1 to 3 percent of the investment. Against this backdrop, the high double-digit million euro figure communicated by Feldschlösschen for a system with 50,000 pallet positions, including rail loading, conveyor technology, and photovoltaics, appears plausible and by no means excessive.
Eleven more journeys, hundreds fewer: The sustainability argument with a hidden agenda
A particularly instructive detail is the project's traffic impact assessment, as it demonstrates how economic and environmental arguments intertwine. A preliminary study estimates a mere eleven trips per day at the site itself. This figure initially sounds insignificant and is being actively promoted by Feldschlösschen – and rightly so, as it forms part of a clever argumentation strategy with authorities and local residents. The real effect lies not at the site itself, but within the overall system. By eliminating the commuter trips to the closed external warehouses, the company's total traffic volume decreases, even if direct truck traffic to the plant increases slightly.
This site consolidation is a prime example of shifting emissions from a diffuse, difficult-to-measure sphere into a transparent, accountable structure. Two further elements enhance the sustainability benefits: Firstly, the two-stage logistics model with sixteen logistics sites in twelve cantons is maintained, with long-distance transport continuing by rail – the new rail loading facility at the high-bay warehouse reinforces this shift to rail. Secondly, the building is equipped with its own photovoltaic system and modern energy and electrical engineering, further reducing operating costs and the warehouse's carbon footprint. For a company under the umbrella of the Danish Carlsberg Group, which pursues ambitious sustainability goals, this combination of cost efficiency and a balanced emissions profile is strategically valuable.
However, it's worthwhile to consider a more objective perspective. The communication surrounding the eleven additional trips is clearly geared towards securing political approval. Furthermore, automated high-bay warehouses are energy-intensive because storage and retrieval machines, conveyor systems, and air conditioning require a constant supply of electricity. The net sustainability effect therefore depends heavily on whether the diesel saved by eliminating the shuttle trips actually more than compensates for the additional electricity consumption of the automation. The photovoltaic system addresses precisely this issue, but realistically, it can only partially cover the costs for a building of this height and throughput.
Your intralogistics experts

Consulting, planning and implementation of complete solutions for high-bay warehouses and automated storage systems - Image: Xpert.Digital
More information here:
The end of external warehouses: Why vertical integration ensures survival in saturated markets
The market context: A beer country on a diet
To fully appreciate the investment, one must understand the market in which it takes place. The Swiss beer market is shrinking structurally and permanently. In the 2024/25 brewing year, sales, including non-alcoholic beers, fell by 1.8 percent to 4.72 million hectoliters, following a decline of 1.6 percent the previous year. Per capita consumption, at around fifty liters, is at a historic low, compared to seventy liters in 1990. This development is not a cyclical anomaly, but rather reflects a profound societal shift: a more active, health-conscious lifestyle in which less alcohol is consumed, but more consciously.
Within this shrinking market, however, there are clear shifts that are highly relevant to the brewing strategy. Non-alcoholic beer is experiencing double-digit growth, increasing by thirteen percent in the last brewing year and now holding a market share of 7.5 percent. At the same time, the former craft beer boom is noticeably slowing, while traditional styles such as lager, pale lager, and pilsner are once again in higher demand. For Feldschlösschen, this means an increasing fragmentation of its product range: more product variations, more non-alcoholic lines, seasonal promotions, and a growing soft drink and mineral water business that partially compensates for the declining beer volumes. The Pepsi brand, which Feldschlösschen produces in Switzerland under license, is a driver of this diversification.
This very complexity of the product range is a strong argument for centralization. A highly automated warehouse can manage a large number of different items with high accuracy and speed – something that is only possible in a distributed network of makeshift warehouses with considerably more effort and a higher error rate. The more heterogeneous the product portfolio becomes, the greater the efficiency advantage of intelligent, software-controlled central logistics. The investment is therefore also a response to the changing nature of demand, not just its declining volume.
The vulnerability of the sales side was particularly starkly illustrated by a single event in 2025. A delivery stoppage to the Migros Group, with its Denner and Migrolino stores, resulting from a price dispute, severely impacted earnings, causing retail sales to plummet by six percent. This incident underscores the extent to which revenues depend on a few powerful trading partners. In such an environment, controlling one's own cost structure is the only variable a company can reliably influence – yet another argument for prioritizing supply chain efficiency.
Feldschlösschen in figures: The investment in context
The following overview categorizes the key project and market indicators and illustrates how the project fits into the operational and market reality.
| dimension | Key figure | Classification |
|---|---|---|
| Building height | 30 meters (plus 5 meters underground) | Required increase of the permissible building height from 20 to 30 meters |
| Base area | approximately 100 × 75 meters | About the size of a football field |
| capacity | 50,000 pallet spaces | Tripleting of storage capacity at the site |
| Investment volume | A high double-digit million amount | Approved by Carlsberg Group Management in Denmark |
| Additional truck traffic | 11 trips per day | At the location; in the overall system, the volume decreases |
| External warehouses to be dissolved | 3 (Wallbach, Kaiseraugst, Läufelfingen) plus others | Elimination of shuttle services |
| Construction period | Spring 2026 to 2030 | Approximately four years |
| Beer sales 2025 | -5 percent | Total sales -3 percent |
| Swiss per capita consumption | approx. 46–50 liters | 70 liters in 1990 |
| Non-alcoholic beer | +13 percent, 7.5 percent market share | The only growing segment |
The intralogistics industry: A multi-billion dollar market caught between boom and bust
Feldschlösschen's decision is embedded in a global megatrend. The worldwide intralogistics market was estimated at around US$57 billion in 2025 and is projected to grow to over US$139 billion by 2034, representing an annual growth rate of approximately 10.4 percent. Within this market, automated storage and order picking systems constitute the largest segment, accounting for around 32 percent. The European market for intralogistics automation is expected to increase from US$6.84 billion in 2025 to US$12.89 billion in 2031, with a growth rate of just under eleven percent. The drivers are the same everywhere: the e-commerce boom, the increasing shortage of skilled workers, and wage inflation, which is making manual processes ever more expensive.
A notable short-term dissonance exists between structural growth and the current economic climate. The German and European intralogistics sector is experiencing a period of stagnation at the beginning of 2026, with German manufacturers' production volume falling by seven percent to €25.8 billion in 2025. Geopolitical uncertainties, a weaker industrial economy, and changes in global supply chains have led to this slowdown, with the sector itself viewing 2026 as the bottoming-out point, from which renewed growth is expected starting in 2027. Investing counter-cyclically during such a phase can prove to be a wise move: capacities at plant engineering companies are more readily available, and those who capitalize on the downturn will be ready with state-of-the-art infrastructure for the next upswing.
The picture is more nuanced for the food and beverage industry in particular. Automated storage systems primarily address high land costs and the need for high-density storage, while miniload systems for smaller units are experiencing disproportionate growth. The established suppliers – from Swisslog and SSI Schäfer to Dematic, Jungheinrich, TGW, and Witron – are technologically mature, which limits the implementation risk for a client like Feldschlösschen. Software, specifically warehouse management systems, is growing faster than hardware because the orchestration of order flow, personnel planning, and robot tasks is increasingly determining competitive advantage.
Skills shortage and automation: The silent driving force
One aspect that is barely mentioned in the public debate surrounding the Rheinfelden warehouse, but is central to the overall economic analysis, concerns the labor market. The shortage of skilled workers and wage inflation are considered independent, medium-term drivers of automation growth, contributing an estimated 2.4 percentage points to the industry growth rate in the EU. Logistics work is physically demanding, particularly strenuous in cold beverage warehouses, and increasingly difficult to fill. Every pallet that will be moved by a storage and retrieval machine instead of a forklift driver in the future decouples the company's operational capability from a shrinking labor supply.
For Feldschlösschen, with its approximately 1200 employees, this decoupling has a strategic dimension that extends beyond mere cost reduction. It means planning security. An automated warehouse operates around the clock, independent of shift availability, sick leave, or wage negotiations. In an aging society with a declining working-age population, this independence is a value in itself. The investment is therefore also a safeguard against a demographic risk that is likely to intensify in the coming decades. The economic rationale is this: capital is readily available and predictable today, while skilled labor is becoming scarcer and more expensive – so one is being substituted for the other.
Long-term planning as a competitive advantage and as a risk
Large-scale intralogistics projects require complex, multi-year planning phases, and the Feldschlösschen case exemplifies this. From the initial revision of the zoning plan by the authorities, through the political participation process involving eight submissions and the approval of the municipal assembly, to the actual construction period of approximately four years, the timeframe extends over well over half a decade. Adding to the complexity was the proximity to the historic castle grounds, which are protected by a conservation agreement and required the approval of the cantonal heritage preservation authorities. This lengthy planning process is typical for this asset class and, at the same time, represents its greatest risk.
Anyone building today for a capacity that will go into operation in 2030 and then be depreciated over decades has to forecast the demand of a market that is structurally declining. This is the real entrepreneurial gamble. Feldschlösschen addresses this risk with two arguments. First, the capacity is deliberately designed with a buffer, so that no external storage will be needed in the future – the tripling is therefore not only geared towards current demand, but also towards a consolidated long-term market. Second, the business is shifting from pure beer to a broad beverage portfolio including non-alcoholic products, mineral water, and soft drinks, the volume of which is more stable than that of the shrinking core product.
Nevertheless, a residual risk of oversizing remains. Should beer consumption decline faster than expected, or should further trade disputes, such as the Migros conflict, permanently impact sales volumes, some of the created capacity could prove superfluous. The profitability of the investment therefore depends significantly on capacity utilization. A highly automated warehouse that is three-quarters full has a considerably worse unit cost balance than one that is fully utilized, because the high fixed costs of the system must be spread across fewer pallets. The strategic response to this is to open the warehouse to the entire beverage business and position it as a distribution hub, not just a beer warehouse.
The corporate perspective: Why Copenhagen signed the check
An often overlooked point is that this investment wasn't decided solely in Rheinfelden. Feldschlösschen has been part of the Danish Carlsberg Group since 2000, and the investment budget was approved by the management in Denmark. For a global corporation to invest a substantial eight-figure sum in a single Swiss location during a period of declining sales is a remarkable commitment. It signals that Carlsberg views the Swiss market, despite its maturity, as a profitable and strategically important location that it intends to secure for the long term.
From a corporate perspective, this capital allocation makes sense because Switzerland is a high-margin premium market, and Feldschlösschen remains the clear number one there with a quarter of the market share – every fourth beer consumed in Switzerland comes from this company. Efficiency investments in such core markets offer a corporation an attractive risk-return profile because they deliver predictable, immediately effective cost savings, rather than relying on uncertain growth projections. In the internal capital competition of a corporation that optimizes locations worldwide, Rheinfelden has thus prevailed over other capital uses – further evidence of the robustness of the underlying calculations.
A model case with signaling implications
What's being built in Rheinfelden is more than just a warehouse for a traditional brewery. It's a lesson in the economic logic of mature consumer goods markets in the 21st century. The key insight is that companies in saturated or shrinking markets no longer defend their profitability through volume growth, but rather through the radical optimization of their value chain. Vertical expansion to combat expensive land, automation to counter labor shortages, centralization to reduce friction, and countercyclical investment to counter economic uncertainty – all these principles are embodied in this single building.
For observers of industrial and logistics developments, this case is revealing because it can be generalized. Wherever established manufacturers face stagnant demand, expensive land, and labor shortages, similar decisions will be made. The beverage industry is merely a particularly vivid example because its product is heavy, bulky, and highly seasonal. The real competition of the coming years will not take place on the supermarket shelf, but in the invisible processes behind it—in the question of who can transport their pallets from bottling plant to retail partner faster, cheaper, and with fewer people. Feldschlösschen's tower by the highway is the answer to this question made manifest in stone, and therein lies its significance beyond this specific case.
Your global marketing and business development partner
☑️ Our business language is English or German
☑️ NEW: Correspondence in your native language!

Konrad Wolfenstein
I and my team are happy to be available to you as your personal advisor.
You can contact me by filling out the contact form here wolfenstein@xpert.digital:or simply call me at +49 7348 4088 965. My email address is
I'm looking forward to our joint project.