Diesel versus principles: Trump lowers the price at the pump – and raises the bill for the West – Creative image on the topic, with AI: Xpert.Digital
Diesel crisis in the USA: Trump's risky bet on Russian energy
Russian diesel: A double-edged sword for the American economy
The hidden costs of Trump's diesel decision: A look at the geopolitical consequences
The United States' decision to import Russian diesel represents a significant turning point in American energy policy. President Donald Trump is responding to the acute diesel shortages and historically high prices at the pump. At first glance, this move may appear to be a pragmatic solution to alleviate pressure on consumers and businesses. However, the political dimension of this strategy is far from unproblematic. Opening the market to Russian diesel not only raises economic considerations but also questions about the effectiveness of Western sanctions against Russia and Ukraine's military strategy.
The complex situation illustrates how closely intertwined energy prices, geopolitical stability, and economic dependencies are. While the short-term relief for American consumers and businesses may seem appealing, the long-term credibility of US sanctions against Russia could be jeopardized. With every tanker that brings Russian oil to American shores, the Western unity that sanctions were intended to achieve could lose credibility. This analysis examines the economic and political implications of the American diesel deal and the risks it poses for Ukraine and Western sanctions policy.
A business that goes far beyond the price at the pump
The announced opening of the American market to Russian diesel appears at first glance to be a pragmatic response to an acute supply shock. The United States is suffering from historically high diesel prices, dwindling inventories, and a global refinery crisis. President Donald Trump is therefore attempting to bring additional supply to the market. Russia is initially expected to provide more than 300,000 tons of diesel, followed by another 500,000 tons in November and shortly thereafter by a further one million tons. Up to three million tons could be added, provided the condition of Russian refineries allows it. The US Treasury Department has created a temporary exemption from sanctions for this purpose, permitting such transactions until April 7, 2027.
Economically, the move is understandable; politically, it is highly risky. The decision connects three areas of conflict that cannot be neatly separated: the fight against high energy prices in the US, the effectiveness of Western sanctions against Russia, and Ukraine's military strategy against Russian energy infrastructure. What Washington is selling as short-term price relief can be considered an economic and diplomatic success in Moscow. For Kyiv, however, the impression is that successful attacks on Russian refineries will not lead to increased pressure on the Kremlin, but rather to American pressure on Ukraine.
This isn't just about whether some tankers carrying Russian diesel are calling at American ports. The crucial question is what signal the largest Western economy is sending to producers, traders, financial institutions, and allies. Sanctions don't work solely through prohibitions. They also work through predictability, political unity, and the conviction that concessions to Russia are tied to verifiable concessions. This very connection is weakened by the temporary reopening.
America's diesel crisis is a refinery crisis
The high American diesel prices cannot be attributed to a single cause. In September 2026, the average retail price was around $6.29 per gallon. A year earlier, it was approximately $3.68 to $3.74. This increase is therefore clearly noticeable not only for trucking companies and farmers, but also for private households and small businesses. At the same time, distillate inventories on the American East Coast in September were around 32 percent below the seasonal average for the years 2021 to 2025. This region is particularly vulnerable because it consumes significantly more diesel and heating oil than its own refineries can produce.
The bottleneck lies less in crude oil itself than in its processing. The US produces large quantities of crude oil and is a significant net exporter of petroleum and petroleum products overall. However, crude oil cannot be used directly in trucks, combine harvesters, or heating systems. It must be processed in refineries, whose technical configuration determines how much gasoline, diesel, kerosene, and other products can be obtained from a barrel of crude oil. If suitable refinery capacity fails or is already operating near its practical limit, additional crude oil will only provide limited relief.
This is precisely why so-called crack spreads have risen sharply. In simple terms, they describe the difference between the price of the crude oil used and the wholesale price of the products derived from it. High spreads indicate that it's not just the raw material itself, but also the processing capacity that is in short supply. In September, diesel crack spreads on the American Gulf Coast and in Northwest Europe temporarily exceeded $100 per barrel. This is an exceptional level and explains why diesel prices can rise significantly more than crude oil prices.
Russian diesel is therefore attractive to Trump because it provides precisely the scarce end product. Releasing strategic crude oil reserves is less effective if refineries cannot process sufficient additional quantities. Imported diesel bypasses this bottleneck. After transport, testing, and distribution, it can reach the market relatively quickly. This makes the approach more effective in the short term than many traditional energy policy measures, but it does nothing to address the structural causes of the shortage.
The global market has lost its reserves
The American situation is part of a much larger supply shock. Since 2019, global demand for liquid fuels has increased more sharply than refinery capacity. At the same time, capacity expansion has been very uneven across regions. China and the Middle East built modern, large-scale refineries, while Europe and North America decommissioned older plants. Thin margins in previous years, high regulatory costs, aging technology, and the expectation of a long-term decline in fuel demand made investments in new Western refineries unattractive.
This development was manageable under normal market conditions. However, it presupposed that international trade flows functioned smoothly, facilities operated reliably, and regional deficits could be offset by imports. In 2026, several disruptions coincided. The conflict in the Middle East affected refinery production and transport through the Strait of Hormuz. Houthi attacks increased risks and costs in the Red Sea. China temporarily reduced its exports of refined products. Russia restricted its exports to supply its domestic market. At the same time, Ukrainian drones increasingly targeted Russian refineries and ports.
At its peak, this resulted in an estimated six to eight million barrels of refining capacity being missing from the global fuel market per day. This corresponds to up to ten percent of global capacity. Crucially, it is not only the absolute quantity but also the simultaneity of these outages. A deficit in the Middle East could normally be offset by increased deliveries from Russia, Asia, or the USA. However, if several regions simultaneously experience reduced production and American refineries are already operating at high capacity, these usual buffers disappear.
Even stockpiles offer only limited help. While large quantities of crude oil and petroleum products exist worldwide in tanks, ships, and pipelines, not every product is located in the right place, meets the required quality standards, or can be transported in time. A heating oil reserve in Asia won't solve a short-term diesel shortage on the American East Coast if ships, insurance, port access, or suitable blending components are lacking. The global energy market therefore theoretically possesses more reserves than are actually available in a specific crisis.
Russia is both a supplier and a bottleneck
Russia's role is contradictory. The country has around 6.5 million barrels of installed refining capacity per day and has traditionally been one of the largest producers of refined petroleum products. Before the recent restrictions, Russia exported roughly half of its diesel and gas oil production. These quantities were particularly important for the global market because diesel is harder to replace than crude oil, and many economies rely on imports.
At the same time, it is unclear whether Russia can actually deliver the announced volumes. Russian refinery throughput fell in June to approximately 3.8 million barrels per day, the lowest level in more than two decades and about 30 percent less than a year earlier. Diesel production is also reported to have fallen by almost 30 percent at times. Russia responded with export bans, increased subsidies, postponed maintenance, the reactivation of idled facilities, and fuel imports.
The quantities under discussion must therefore be considered in a differentiated manner. The first 300,000 tons are relevant for the world market, but represent less than a tenth of global daily demand. They can influence sentiment on the futures markets and dampen short-term price spikes, but they do not resolve the structural bottleneck. The next tranche of 500,000 tons would be more noticeable, provided it is in addition to the already expected supply. However, the millions of tons announced beyond that are expressly contingent on functioning refineries. This is precisely where the greatest doubts lie.
Then there's the question of time. Between a political announcement and a physical delivery lie loading, financing, insurance, transport, unloading, and distribution. Even if individual shipments are released quickly, the broader effect on American retail prices is delayed. Forward prices can react immediately because traders adjust their expectations. At the pump, however, wholesale prices are only passed on gradually. The political message of rapid relief is therefore more certain than actual relief.
Ukraine is hitting Russia's most sensitive industrial point
The Ukrainian attacks on Russian refineries follow a clear economic and military logic. Crude oil fields and pipelines are widely dispersed and often difficult to disable effectively. Refineries, on the other hand, consist of complex, stationary, and capital-intensive facilities. Particularly vulnerable are not only the distillation units, but also hydrocrackers, reformers, desulfurization plants, and catalytic crackers. These components increase the yield of high-quality fuels and ensure that diesel and kerosene meet modern quality standards.
Minor damage to simple distillation units can sometimes be repaired within a few weeks. Severely damaged secondary equipment, on the other hand, often requires six to eight months or longer. Sanctions make it difficult for Russia to access Western specialized technology, spare parts, and engineering services. Repeated attacks further increase wear and tear because maintenance is postponed, spare parts are used up, and provisionally repaired units are subjected to renewed stress. In 2026, a Russian refinery was hit on average about every three days. Some plants have already been subjected to up to 15 attacks since the start of the war.
The economic impact extends beyond the immediate loss of production. Refineries transform crude oil into higher-value products. If this processing ceases, Russia may be able to export more crude oil, but often achieves lower margins and has to accept larger price reductions. At the same time, costs arise for repairs, air defense, operational disruptions, and government support measures. Between April and August 2026, Russian oil companies received subsidies totaling approximately 1.5 trillion rubles to stabilize the domestic market.
For Ukraine, this strategy offers a way to burden Russia's war economy with its own technological capabilities. It aims to simultaneously put pressure on fuel supplies, export revenues, and the state budget. American access to diesel fuel changes this calculation. If Moscow is allowed to resume exports through a political agreement, and in return Washington presses for an end to Ukrainian attacks, the Kremlin can transform some of the military damage into diplomatic gain.
Short-term relief comes at the expense of long-term credibility
From an American perspective, the conflict of objectives is real. A president cannot ignore the fact that diesel prices exceeding six dollars per gallon burden agriculture, logistics, construction, and consumers. The midterm elections on November 3rd intensify the pressure to act. High fuel prices are immediately visible, unevenly distributed regionally, and easily attributable to political factors. They particularly affect key Republican voter groups in rural areas where agriculture and road freight play a major role.
Economic common sense therefore does not require rejecting every additional ton of Russian imports outright. In an acute shortage, a temporary exception can mitigate damage to businesses and households. However, the specific design is crucial. Easing sanctions without transparent concessions is different from a narrowly defined humanitarian or market-stabilizing exception tied to verifiable conditions. Possible exceptions include a ceasefire for energy infrastructure, a limitation of Russian attacks on Ukrainian power plants and ports, or a mechanism that partially freezes revenues.
The current arrangement, however, gives Russia an early economic advantage. Moscow can generate additional revenue, relax its export policies, and present itself as an indispensable stabilizer. Ukraine receives no comparable security guarantee. This creates an asymmetrical deal: The US gains the prospect of lower prices, Russia gains market access and political standing, while Ukraine is expected to forgo a strategic bargaining chip or at least face increasing pressure.
The credibility of sanctions depends heavily on whether exceptions are perceived as rare, rule-based, and reversible. If they are changed at short notice due to domestic political pressure, market participants will anticipate further relaxations in the future. Banks, shipping companies, and traders might increase their willingness to prepare business deals with Russian companies. Conversely, allies might doubt the reliability of American commitments. The immediate price of diesel is measurable; the value of lost credibility doesn't appear in any weekly statistics, but it can be greater in the long run.
Diesel is the invisible price of almost all goods
Diesel differs from gasoline in political and economic terms. Gasoline prices directly affect drivers and are therefore particularly noticeable. Diesel has a greater impact through production and supply chains. Trucks, agricultural machinery, construction equipment, parts of the rail network, industrial plants, and heating systems all rely on diesel fuel. Rising diesel prices therefore increase costs from the field to storage and on to the retail level.
Companies initially react differently. Freight forwarders can pass on higher fuel costs to shippers via variable surcharges. Farmers often only have this option during later contract negotiations or through higher selling prices. Retailers can absorb some of the burden through lower margins, but will also pass on sustained cost increases. The transmission to consumer prices therefore occurs gradually and can take six to eighteen months.
A rule of thumb among American economists states that a sustained one-dollar increase in diesel prices can raise general inflation by approximately 0.1 percentage points. Other models predict significantly stronger effects from a diesel-related price shock of around 15 percent, depending on the duration, initial conditions, and monetary policy response. Such estimates are not absolute truths. However, they demonstrate that diesel cannot be treated as a minor subcategory of the energy market.
The food industry is particularly vulnerable. Diesel powers tractors, harvesters, and trucks, and simultaneously influences the costs of many intermediate products. In the fall, the price shock coincides with the harvest season. Added to this are cold chains and long transport routes within the American domestic market. Easing diesel emissions could therefore indeed limit broader inflationary effects. This is the strongest economic argument for Trump's decision. However, it does not explain why the easing of restrictions must occur without any discernible security policy concessions in return.
Our US expertise in business development, sales and marketing

Our US expertise in business development, sales and marketing - Image: Xpert.Digital
Industry focus areas: B2B, digitalization (from AI to XR), mechanical engineering, logistics, renewable energies and industry
More information here:
A thematic hub offering insights and expertise:
- Knowledge platform covering global and regional economies, innovation and industry-specific trends
- A collection of analyses, insights, and background information from our key areas of focus
- A place for expertise and information on current developments in business and technology
- A hub for companies seeking information on markets, digitalization, and industry innovations
Strategies for stabilizing diesel prices
The price impulse can be greater than the physical quantity
Commodity and product markets react not only to actual deliveries but also to expectations. Following the announcement, American diesel futures contracts temporarily fell by around five percent. This reaction shows that even the prospect of additional Russian exports can reduce risk premiums. Traders are not only calculating based on the first 300,000 tons but also on the possibility of further deliveries, a relaxation of the Russian export ban, and a political easing of tensions in the energy sector.
This expectation effect is politically valuable for Trump. A rapid movement in the futures markets can be presented as a success, even if the physical deliveries haven't yet arrived. Falling wholesale prices can be passed on to gas stations with a delay. However, this very mechanism cautions against exaggerated expectations. If Russia delivers less than announced, new refineries fail, or the geopolitical situation escalates, the price decline can quickly reverse.
Furthermore, it is crucial whether the Russian quantities are truly additional. If only shipments that would otherwise have gone to other customers are rerouted, the regional supply in the US will improve, but the global supply will hardly increase. Other buyers will then have to pay higher prices or find alternative suppliers. The global relief will be less than the gross volume would suggest. Only if Russia relaxes its export ban and actually releases previously withheld production onto the world market will there be a clear net effect.
The announced agreement is therefore more of an option for relief than a guarantee. In the short term, it reduces fears of extreme shortages. Whether it will permanently change price levels depends on refinery repairs, further Ukrainian attacks, Russian domestic demand, transport capacity, and developments in the Middle East. A single bilateral deal can mitigate a global refinery shock, but it cannot eliminate it.
Putin's economic gain is greater than the sales revenue
For Russia, the benefit isn't just the additional foreign currency earnings. The more significant gain lies in its political standing. As recently as early October, Vladimir Putin had declared that Russia would not supply diesel to the global market as long as sanctions remained in place. Just a few days later, Washington granted a temporary exception. The Kremlin can portray this as evidence that Western pressure is easing under economic strain.
The agreement also helps to shift the narrative of responsibility for high global energy prices. Russia can argue that it is prepared to supply energy if sanctions are lifted and attacks on refineries cease. This shifts the focus away from Russia's war of aggression and Moscow's own export restrictions, and instead places Ukraine's defensive strategy and Western sanctions at the forefront. This narrative is attractive to countries that prioritize low energy prices over European security interests.
Fiscally, Russia's situation remains strained. Revenues from oil and gas in the first eight months of 2026 were almost 17 percent lower than the previous year. The budget deficit reached approximately 5.8 trillion rubles, already exceeding the deficit for the entire previous year. At the same time, military spending, subsidies, repair costs, and expenditures for securing critical infrastructure are increasing. Additional diesel sales will not solve these problems, but they will improve liquidity and forecasts.
The potential precedent-setting effect is particularly valuable for Moscow. If a major sanction is suspended for reasons of price stability, similar arguments can later be used for other products or longer timeframes. Russia does not necessarily need to achieve a formal lifting of the entire sanctions regime for this to happen. Even a growing network of exceptions reduces its practical scope and increases the costs of Western coordination.
Kyiv is losing influence on two levels
For Ukraine, the American decision is problematic both materially and strategically. Materially, higher Russian energy revenues could stabilize the state budget and thus indirectly facilitate the continuation of the war. Not every dollar from a diesel sale flows directly into military spending. However, in a centralized war economy, additional export revenues increase the state's fiscal leeway.
Strategically, the issue is the value of Ukrainian attacks on refineries. This campaign has forced Russia to conserve diesel and other fuels domestically, relax quality standards, organize imports, and pay high subsidies. It thus affects not only military supplies but also the political economy within Russia. Fuel shortages and long waiting times make the costs of the war more visible to the population.
If the US now facilitates Russian exports while simultaneously demanding an end to attacks on Ukrainian refineries, the impact of this campaign will be partially neutralized. Kyiv could face the choice of scaling back a militarily effective approach without receiving equivalent Russian restraint. Ukraine has offered to cease attacks on Russian refineries if Russia, in turn, stops destroying Ukrainian energy facilities. Such reciprocity would be negotiable and verifiable. According to publicly available information, the current diesel agreement does not contain any such obligation.
Furthermore, this process undermines confidence in coordination with Washington. If bilateral US-Russian agreements affect core economic interests of Ukraine without visibly involving Kyiv, the value of Ukrainian negotiating offers diminishes. Russia is incentivized to negotiate directly with the US on sanctions and energy markets, rather than making military concessions to Ukraine.
Europe's problem doesn't begin on the US coast
Europe is doubly affected by this development. First, the European diesel market is structurally dependent on imports and is more severely impacted than the American market by the loss of Russian and Middle Eastern supplies. Low water levels on the Rhine, high transport costs, and the decommissioning of older refineries are exacerbating regional bottlenecks. European buyers are therefore increasingly turning to American diesel exports.
If the US imports more Russian diesel, this could ease pressure on the global market. At the same time, however, Washington could capture a larger share of available supplies for its own needs. The net effect for Europe depends on whether Russia increases its overall exports or merely redirects trade flows. With genuine additional production, Europe benefits from lower global market prices. With mere diversion, it indirectly competes with the US for other available quantities.
Secondly, the deal affects European sanctions policy. The European Union has sought to limit Russian revenues from oil and petroleum products and to make it more difficult to circumvent sanctions through third countries. An American exception weakens political unity, even if European rules formally remain unchanged. Companies then question whether strict European restrictions will hold up in the long run if Washington, under domestic political pressure, pursues its own course.
This presents European governments with a difficult dilemma. They can maintain the sanctions and risk higher short-term energy costs. Or they can consider similar exemptions and thus further reduce economic pressure on Russia. The more sensible response would be a common, strictly conditional agreement. It would have to clearly define quantities, timeframes, eligible contracting parties, payment methods, and reciprocal obligations. Unilateral national actions, on the other hand, increase Russia's negotiating power.
Strategic reserves solve the wrong problem
The United States and other industrialized nations have already attempted to curb price increases by releasing strategic reserves. In early October, under American pressure, the G7 agreed to accelerate the release of approximately 100 million barrels of oil and diesel. Such measures can prevent panic and bridge supply gaps. However, their effectiveness depends on the composition of the reserves.
A large portion of government reserves consists of crude oil. In a refinery crisis, crude oil is less helpful than finished diesel or suitable intermediate products. The U.S. strategic petroleum reserve stood at approximately 284 million barrels in September, its lowest level since 1982. Further withdrawals reduce the buffer against future disruptions. Moreover, a technically necessary minimum stock must remain in the system to ensure the continued operation of caverns, pipelines, and terminals.
A ban on American diesel exports would also be problematic. While it might keep more fuel domestically in the short term, it would raise international prices and burden allied importing countries. Since Europe now imports additional distillates from the US, an export ban could exacerbate shortages there. Higher global market prices would, in turn, incentivize American traders to seek loopholes and could have repercussions for other products in the US market.
Tax breaks for motorists or the temporary use of tax-advantaged off-road diesel may lower individual fuel bills, but they don't create any additional fuel supply. In fact, they may even increase demand and shift costs to the state budget. Russian imports, by comparison, are more plausible from a market perspective because they at least potentially increase the physical supply. Precisely for this reason, it would have been possible to link this exception to clear political conditions.
The midterms shorten the economic policy horizon
The timing, just weeks before the midterm elections, shapes the decision. Energy prices have high political visibility, while their causes are complex and international. Voters experience the price at the pump daily, but not the utilization rate of a Russian hydrocracker, the storage levels on the East Coast, or the insurance premium of a tanker. Governments therefore have a strong incentive to choose measures that have a short-term, visible impact.
Trump is specifically targeting his message at farmers, ranchers, and truck drivers. These groups are disproportionately affected by diesel prices and are concentrated in politically important rural areas. A credible prospect of falling prices can therefore have an impact even before actual delivery. Even a limited decline in futures prices supports the narrative that the president has taken action while other actors merely discuss sanctions and long-term strategies.
The political problem lies in the fact that short-term relief and long-term costs are separated in time. A lower diesel price before election day is immediately attributable. A weakened sanctions architecture, greater Russian negotiating power, or lower Ukrainian trust become apparent later and are more difficult to measure. This asymmetry favors decisions that are rational domestically but costly internationally.
Nevertheless, it would be too simplistic to dismiss this move as merely an election ploy. The diesel shortage is real, the risk of inflation is considerable, and the burden on productive sectors is substantial. A responsible analysis must acknowledge both: Trump is addressing a genuine economic problem, but he is choosing a tool whose geopolitical repercussions do not appear to be adequately mitigated.
What a viable solution would need to contain
A more economically and security-politically viable agreement would need to combine five elements without creating a rigid sanctions regime. First, a clear quantitative limit would be necessary. Only volumes that demonstrably contribute to the global market should be released, and not merely diverted from other delivery destinations. Second, the duration and automatic termination would need to be clearly defined to prevent an emergency measure from becoming permanent market access.
Third, payments should be processed transparently and, if necessary, partially held in controlled accounts. This would prevent the entire proceeds from flowing unchecked into the Russian state budget. Fourth, the exception would have to be tied to verifiable de-escalation. Mutual protection of energy infrastructure would be an obvious solution: Ukraine suspends attacks on Russian refineries, while Russia ceases attacks on Ukrainian power plants, grids, ports, and fuel depots.
Fifth, joint American-European oversight is needed. Differing rules create loopholes, distort competition, and fuel political disputes. A coordinated mechanism could cover ships, insurers, banks, refineries, and end users. It could also provide for the immediate suspension of the exemption if Russia violates agreed-upon conditions or manipulates delivery volumes.
Such a structure would be more complex than a blanket license. However, it would avoid the central flaw of the current decision: Russia would not receive economic relief simply for its willingness to sell a scarce product, but only in exchange for a verifiable contribution to de-escalation. Market relief and security policy would thus not be pitted against each other.
The West needs more than crisis imports
In the long term, the crisis demonstrates that Western energy policy must link the transition to more climate-friendly propulsion systems with the security of supply of existing systems. The expectation of declining oil demand has dampened investments in refineries. At the same time, freight transport, agriculture, construction, shipping, and aviation will remain dependent on liquid energy carriers for a long time to come. If old capacities disappear faster than demand and alternatives emerge, vulnerability to geopolitical shocks increases.
This doesn't mean indiscriminately building new conventional refineries. Such plants are expensive, require lengthy permitting and construction phases, and could face declining demand over their lifespan. More sensible approaches include targeted modernizations, flexible hydrocrackers, additional distillate storage capacity, improved port and pipeline connections, and a broader geographic supply base. Renewable diesel, synthetic fuels, and more efficient logistics can also alleviate the pressure.
The American East Coast, in particular, needs more resilient supply routes. There, limited regional refining capacity, high winter demand, and import dependence converge. Additional storage facilities and improved connections to the Gulf Coast could reduce reliance on short-term overseas imports. At the same time, Europe must make its inland logistics more resilient and address bottlenecks on rivers, in ports, and in pipelines.
The most important lesson is that crude oil independence does not automatically guarantee fuel security. A country can produce record quantities and still suffer from diesel shortages if refineries, product storage facilities, and transportation infrastructure are lacking. Strategic energy policy must therefore consider the entire value chain. Otherwise, every new crisis will once again lead to frantic approvals, exceptions, and political deals.
A lower price can become very expensive
Trump's agreement could work in the short term. The mere announcement of additional Russian shipments lowers the risk premium in the market. Actual deliveries could stabilize American inventories, relieve pressure on freight companies and farmers, and limit inflationary pressure. In a tight supply situation, it would be economically irresponsible to downplay these benefits.
However, it would be equally irresponsible to focus solely on the price at the pump. The US is easing a sanction intended to limit Russian energy revenues and thus the Kremlin's financial leeway. This comes after Ukrainian attacks on refineries caused measurable production losses, export restrictions, and high fiscal costs. Russia is thus receiving relief at a point where the pressure was particularly effective.
The crucial flaw lies not in the import itself, but in the lack of consideration in return. Time-limited access to diesel could be part of a balanced arrangement if it were linked to verifiable protection of Ukrainian energy infrastructure, controlled payment flows, and close coordination with Europe. Without such conditions, it appears to be an advance payment to Moscow, financed by Ukraine's strategic position.
The sober perspective is therefore this: The deal is economically understandable, but in its currently discernible form, geopolitically undervalued. Trump is buying potential price relief with political credibility. Whether this deal pays off for the US will not be decided by the first fuel price displays, but by whether Russia actually delivers additional quantities, whether the sanctions pressure is permanently weakened, and whether Moscow uses the resulting relief for negotiations or for a protracted war.
🎯🎯🎯 Data-driven B2B industry hub as a quasi-in-house solution

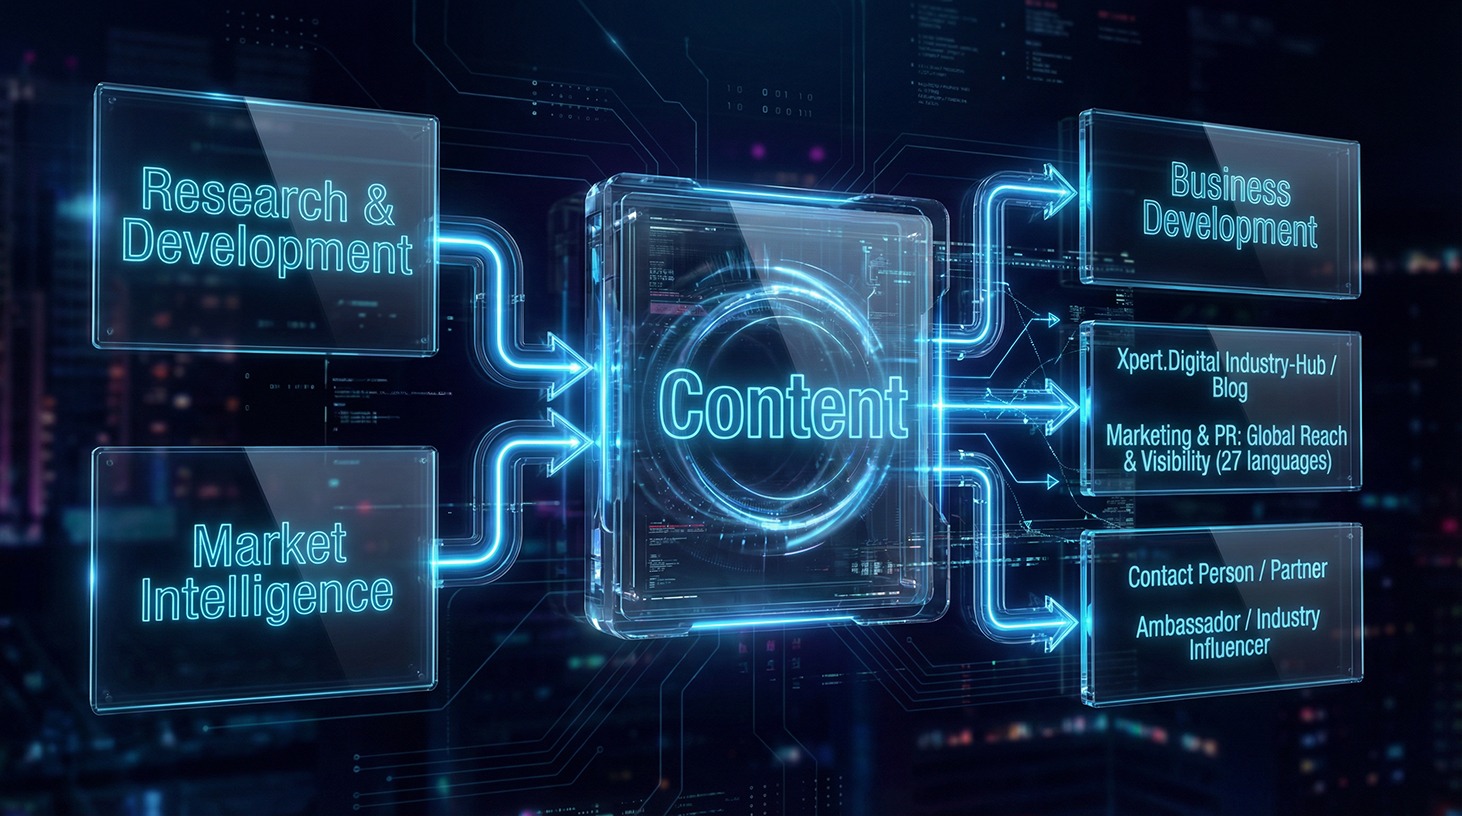
The quasi-in-house solution: How Xpert.Digital closes operational gaps in B2B marketing and sales – Smart Content-Driven Business - Image: Xpert.Digital
Xpert.Digital is a data-driven B2B industry hub led by Konrad Wolfenstein . The company acts as an external, quasi-in-house solution for industrial partners, closing operational gaps in marketing, content, and sales – without requiring additional resources on the client side.
More information here:
Your global marketing and business development partner
☑️ Our business language is English or German
☑️ NEW: Correspondence in your native language!

Konrad Wolfenstein
I and my team are happy to be available to you as your personal advisor.
You can contact me by filling out the contact form here wolfenstein@xpert.digital:or simply call me at +49 7348 4088 965. My email address is
I'm looking forward to our joint project.