Meta vs. Amazon: Who will control AI-powered shopping in the future? Is Amazon blocking Meta's AI agents? Here's what's behind the conflict – a creative image on the topic, featuring AI: Xpert.Digital
AI agents are changing online retail – and Amazon's advertising business
Whoever controls the shopping assistant could earn a lot of money in the retail sector
The next major power struggle in online retail may not be decided between two marketplaces, but rather at a new interface: the AI shopping assistant. Meta's Muse is designed to search for products, compare offers, and complete purchases according to users' preferences. Amazon has banned the agent from its platform, citing security and data privacy concerns. At the same time, the company is expanding its own shopping assistant with Alexa for Shopping. The conflict, therefore, isn't simply about whether artificial intelligence is changing commerce. The crucial question is who will mediate between customer desires and orders in the future – and thus influence which products even make the shortlist. For Amazon, more is at stake than just the sale of individual goods: its multi-billion-dollar advertising business could also be affected if external agents shift product searches away from the marketplaces. However, millions of registered Muse users are not yet proof of a fundamental shift. How great the risk actually is for Amazon, and whether AI agents will open up commerce or merely create a new intermediary power, depends on how frequently consumers use them and to whom they entrust their purchasing decisions.
Meta vs. Amazon: How AI shopping agents are redistributing power in online retail
Whoever controls the shopping assistant may be liable for the next trade tax
The next major power struggle in online retail may not be between two marketplaces, but rather between two paths to the purchasing decision. On one side is Amazon with its extensive product range, logistics, customer data, and multi-billion-dollar advertising business. On the other side are AI agents that can search for products for consumers, compare offers, and place orders under predefined conditions. Meta's assistant, Muse, makes this conflict visible: If the customer no longer navigates an online shop themselves, the operator loses some control over which products receive attention.
More than ten million people in the US and Canada set up a Muse agent within the first six weeks. This figure, cited by Meta, demonstrates significant initial interest but doesn't yet prove ten million regular customers. Amazon has banned Muse from shopping on its platform, citing security and privacy concerns. At the same time, the company is further developing its own AI-powered shopping interface, Alexa for Shopping. This isn't simply a case of technological progress versus its prevention. Both companies are committed to automated shopping. The point of contention is who controls and profits from this automation.
The key economic shift, therefore, does not lie in the mere use of artificial intelligence. It lies in the potential relocation of the customer interface. Whoever operates the digital shopping assistant can influence which retailers are considered, which products make it onto a shortlist, and which criteria are deemed decisive for a purchase. The marketplace remains important, but could lose some of its previous role as the starting point for product searches.
The digital warehouse becomes an executing provider
The classic platform model combines several functions. A customer discovers a product, compares alternatives, reads reviews, sees advertisements, chooses a seller, and pays. Amazon bundles these steps into a largely closed environment. The economic advantage arises not only from selling an item, but from controlling the entire process.
An external AI agent can break this connection. For example, the user might specify that they are looking for a quiet vacuum cleaner suitable for a certain apartment size, have a price limit, and value affordable spare parts. The agent translates these requirements into search and evaluation criteria. It could then compare multiple retailers and present only a well-founded selection.
In this model, the shop is no longer necessarily the place where the decision is made. It may only be accessed once the product has already been decided upon. Its role is primarily to reliably deliver an available item at an acceptable overall price.
This changes the distribution of economic power. A retailer can still generate high sales and yet lose influence if another player determines the demand that reaches them. What matters is not only who executes the transaction, but also who selected the alternatives beforehand.
Such a change would not, however, completely disempower retailers. Product range, delivery speed, returns processing, and trust would remain relevant. Rather, individual functions that are currently often organized within the same platform would be separated.
Ten million registrations are a signal, but not yet a business model
Muse's rapid growth deserves attention, but it needs to be carefully considered. Registering is initially a decision to try it out. It reveals little about how frequently the assistant is used, which tasks it actually performs, and whether users will entrust it with long-term financial decisions.
For an economic evaluation, several levels must be distinguished. Registered accounts constitute the potential user base. Regularly active users indicate whether the service is well-received in everyday life. Shopping sessions describe usage for commercial purposes. Completed orders document transactions. Only repeated purchases and a strong customer relationship reveal whether a permanently relevant sales channel is emerging.
Furthermore, a distinction must be made between support and autonomy. An assistant that summarizes product information changes commerce differently than an agent that independently selects retailers, processes payments, and organizes reorders. Both can appear as AI-driven purchasing, but they intervene in the value chain to varying degrees.
Equally important is the question of whether Muse generates new demand or replaces existing sales channels. If a consumer was already planning to buy an item and simply uses a different access point, the overall market doesn't automatically grow. Initially, customer access, advertising effectiveness, and potentially commissions will shift.
The early user numbers primarily demonstrate that a significant portion of consumers are willing to try personal digital assistance. Whether this leads to a new market order depends on reusability, reliability, and economic viability. The current adoption rate is a strategic warning signal for established platforms, but not yet conclusive evidence of their displacement.
Why Amazon's advertising business is particularly exposed
The economic significance of this becomes clear when considering the sheer scale of Amazon's advertising revenue. In fiscal year 2025, the company generated approximately $68.6 billion from advertising services. The frequently cited figure of nearly $70 billion refers to this completed fiscal year. It is not a current upper limit: In the twelve months leading up to the end of September 2026, corresponding revenues had already reached approximately $78 billion. This metric encompasses various advertising formats and should not be equated solely with sponsored product search results.
However, product-related advertising is closely linked to previous purchasing behavior. Someone searching for a specific item on a marketplace is often closer to making a purchase than someone who happens to see a general advertisement. This proximity to the purchase decision makes visibility valuable.
Merchants therefore don't compete solely on product quality, price, and delivery performance. They also pay to be noticed at a crucial moment. This creates an additional revenue stream for the platform operator, alongside their core trading and service business.
An external agent could weaken this logic by preparing the selection outside of the visible search results. The customer would then potentially no longer have to sift through long lists of results and would see fewer sponsored placements. The product could still be ordered from Amazon, but some of the previous advertising exposure would be lost.
This possibility explains why the conflict extends beyond a single assistant. The threat isn't necessarily that Amazon will ship fewer packages. It could be that these same packages come with less control over product selection and advertising.
Not every automated purchase means lost advertising
However, this risk does not mean that AI agents will eliminate advertising altogether. Such a conclusion would underestimate the adaptability of digital business models.
Advertising can change its place. Instead of a featured product within a search results list, a funded recommendation, a sponsored conversation starter, or paid inclusion in a pre-selection list could become economically relevant in the future. Whether and in what form such models prevail depends on labeling, regulation, and user acceptance.
The number of decisions could also change. If an assistant simplifies the buying process, more purchase intentions could actually result in orders. A smaller number of visible advertising slots wouldn't necessarily lead to a proportional decline in revenue. A smaller, particularly effective advertising inventory could command high prices.
Conversely, a single contact can lose value if the agent primarily handles pre-arranged repeat purchases. Someone who reorders the exact same printer cartridges hardly needs additional persuasion through an advertisement.
The economic impact therefore depends on which tasks are automated and who operates the agent. An external assistant can bypass Amazon's advertising contacts. An internal assistant can repurpose them and simultaneously gather additional information about customer preferences.
The real dichotomy, therefore, is not advertising or no advertising. It is: Who has the right and the ability to market access to the purchasing decision?
Amazon is powerful, but it's not synonymous with all of retail
The notion of a shopping monopoly exaggerates Amazon's significance, but it is too imprecise as an economic diagnosis. A reliable assessment of market power requires a clearly defined market. Online retail, the entire retail sector, specific product groups, marketplace services, and digital advertising represent different levels of analysis.
Amazon can be particularly influential in certain sectors without controlling every sales channel. Brick-and-mortar retailers, specialized online shops, other platforms, and direct sales remain independent alternatives. Competitive conditions also vary between countries and product categories.
Furthermore, a platform's strength cannot be measured solely by its revenue. Its dependence on retailers, its importance as a search starting point, and the costs of switching providers are also relevant. A provider can be economically difficult to replace, even if several competitors formally exist.
AI agents could reduce some of these switching costs. If an assistant automatically searches multiple shops and is familiar with different ordering processes, consumers would have to invest less time in their own search. This could allow smaller retailers to be considered more often.
However, this does not mean that every provider has the same opportunity. The agent, in turn, may favor certain dealers, for example, due to technical integration, reliable data, or commercial agreements. The current concentration could therefore weaken, continue, or shift to a new level.
Security concerns and business interests are not mutually exclusive
Amazon justifies the suspension of Muse, among other things, by stating that the agent does not sufficiently identify itself during access and could potentially access sensitive account information. The company also claims not to have authorized the access. Meta presents a different view of its service's security architecture. Therefore, the opposing positions should not be treated as definitively settled technical facts. What is clear, however, is that identification, access rights, and data processing are at the heart of the conflict.
Such questions are economically relevant. An agent could accidentally order the wrong version, change a delivery address, or perform an action the user did not intend. Unclear permissions also increase the risk of account misuse or the unauthorized disclosure of sensitive information.
At the same time, it would be an oversimplification to interpret the block solely as a security measure. Amazon is also protecting its direct customer relationships. If an external agent controls the purchase, another company gains valuable insights into buying intentions and decision-making patterns.
Both motives can exist simultaneously. A platform operator can formulate legitimate security requirements and still have a commercial interest in keeping competitors away from its customer interface.
The decisive factor in the assessment is therefore whether security requirements are verifiable, proportionate, and fundamentally achievable. Between a blanket block and uncontrolled access lies a wide spectrum of possible solutions: verified agent identities, limited permissions, documented interfaces, and revocable purchase authorizations.
Alexa for Shopping shows that Amazon is not fighting against agents
Amazon's own development makes it clear that the company is not fundamentally opposed to automated shopping. The shopping assistant, previously known as Rufus, was rebranded as Alexa for Shopping in May 2026. According to the company, more than 400 million customers used the service within twelve months. This figure demonstrates the reach of an existing retail platform, but due to differing timeframes and usage definitions, it is not directly comparable to early Muse registrations.
This gives Amazon a significant advantage: it doesn't have to establish a shopping assistant separately from an existing purchase process. The feature can be offered where customers are already searching, paying, and managing their orders.
Furthermore, an internal assistant can generally be closely linked to available product, inventory, and delivery information. An external agent, on the other hand, must gather such information via the respective accessible dealer interfaces or interfaces.
Amazon also already has relationships with merchants, payment information, and a well-established fulfillment infrastructure. This combination can reduce errors and simplify purchasing, provided the systems work together reliably.
The strategic conflict therefore lies between different forms of integration. Amazon wants to embed the assistant within its commerce environment. Meta is trying to position the assistant as a comprehensive access point to various providers. The question is whether consumers benefit more from the depth of a single ecosystem or from the breadth of a cross-retailer comparison.
🎯🎯🎯 Data-driven B2B industry hub as a quasi-in-house solution


The quasi-in-house solution: How Xpert.Digital closes operational gaps in B2B marketing and sales – Smart Content-Driven Business - Image: Xpert.Digital
Xpert.Digital is a data-driven B2B industry hub led by Konrad Wolfenstein . The company acts as an external, quasi-in-house solution for industrial partners, closing operational gaps in marketing, content, and sales – without requiring additional resources on the client side.
More information here:
Future scenarios for online retail: Openness vs. control
Why Amazon's competitors view openness differently
For a retailer who expects additional demand from a new agent, the collaboration can be attractive. However, someone who already possesses particularly valuable direct customer access must weigh potential additional sales against the loss of their own control.
This explains why companies can reach different decisions even when considering the same technology. Walmart, Shopify, and other providers have been more open to Muse than Amazon. This doesn't automatically mean they take security concerns less seriously. Their economic starting points and expectations for increased reach may differ.
For a smaller retailer, an agent can create new access to customers who otherwise wouldn't have found their shop. For a large platform, however, the same agent can replace an existing access point that was previously directly controlled and monetized.
These differences can be described as the ratio of additional demand to displaced domestic demand. The larger the additional share, the more attractive openness appears. The higher the risk of displacement, the stronger the incentive for isolation or strictly controlled cooperation.
Even open models can become more restrictive later on. If an agent becomes an indispensable intermediary and demands higher fees, the interests of their trading partners can change. Therefore, today's openness is not definitive proof of permanently aligned interests.
The new scarcity is called trust in the pre-selection
An AI agent can drastically reduce the number of visible alternatives. For consumers, this is initially convenient: instead of checking hundreds of offers, they receive a few well-founded recommendations. However, from a business perspective, inclusion in this pre-selection process becomes particularly valuable.
In a traditional search environment, a user can view further results or modify their search. A persuasively worded recommendation, on the other hand, can give the impression that the essential checks have already been completed. This makes the quality of the selection criteria all the more important.
For example, an assistant must decide how to weight price, durability, delivery time, energy consumption, and brand trust. These characteristics cannot always be objectively condensed into a single ranking. A low purchase price may be associated with higher subsequent costs. Fast delivery may be less important than repairability.
Furthermore, there is the question of conflicts of interest. An agent acting on behalf of a consumer should consider their instructions. Their operator may simultaneously seek revenue from referrals or advertising. Without transparency, a familiar problem arises in a new form: the customer has limited ability to discern whether the recommendation serves their interests or the intermediary's business model.
The new scarcity is therefore not merely about attracting attention. It is credible, verifiable expertise in selection. Those who consistently deliver this can build a strong position. Those who over-monetize it risk the loss of trust upon which the entire model is based.
Product data becomes part of the distribution system
For brands and retailers, agent-assisted purchasing is shifting the importance of their product information. What previously seemed primarily about catalog maintenance is increasingly becoming a prerequisite for being reliably selected in the first place.
An agent needs the clearest possible information regarding variants, dimensions, materials, compatibility, and scope of delivery. Missing information creates uncertainty. Contradictory information can lead to incorrect comparisons. An attractive product then risks being eliminated from consideration, even though it would be objectively suitable.
The distinction between product identity and offer is particularly important. The same item can be available from different retailers with varying shipping costs, delivery times, and return policies. A meaningful comparison must combine these aspects, rather than simply juxtaposing similar product names.
Qualitative characteristics must also be clearly documented. Repairability, spare parts availability, and durability cannot be replaced by arbitrary advertising slogans. The more concretely a manufacturer can demonstrate such characteristics, the easier they can be incorporated into a comprehensible selection process.
The economic consequences are significant: data quality can directly determine visibility and thus sales opportunities. Investments in consistent product information are therefore not just a technical obligation; they can become a key sales investment.
The lowest price is rarely the complete economic answer
The expectation that AI agents will automatically always select the cheapest offer is too simplistic. A well-designed shopping assistant should optimize the benefits according to the customer's specifications, not solely minimize the displayed price.
A seemingly inexpensive device can incur high operating costs. A cheap replacement part might be unsuitable. A low price loses its appeal if delivery is unreliable or returns are complicated. Depending on the product, lifespan, maintenance, and resale value are also relevant.
Agents could consider such differences more systematically than a consumer acting under time pressure. This would represent a potential welfare gain: decisions would be more strongly aligned with the actual overall benefit.
This improvement, however, requires sufficient data. If follow-up costs are unknown or quality specifications cannot be verified, the assessment remains incomplete. A precisely formulated recommendation is not automatically a precisely calculated recommendation.
This presents brands with an opportunity for objective differentiation. Those who can justify higher prices through demonstrable durability, lower operating costs, or better service don't necessarily have to lose out in automated comparisons. The main pressure comes on price premiums whose benefits are neither comprehensible nor relevant to the customer.
Greater price transparency can reduce margins and increase efficiency
If agents can more easily compare offers, price competition could intensify. Standardized items, where identical products are offered by many retailers and the services differ only slightly, would be particularly affected.
In such markets, price differences are partly due to consumers not checking every alternative. If the search effort decreases, these differences can come under greater pressure. Retailers would have to adjust their prices more frequently or highlight other advantages more clearly.
From a consumer perspective, this is attractive, but from a company perspective, it's not just a matter of lower margins. An agent can also reduce costs, for example, if customers order unsuitable products less often or if questions are clarified before the purchase.
The net impact therefore depends on the interplay of several factors: selling price, customer acquisition costs, return rate, service expenses, and repurchase rate. A lower price can be economically viable if the cost per successful order decreases simultaneously.
Conversely, a distribution channel that generates additional revenue but combines high commission fees and strong price pressure would be problematic. Therefore, retailers should not evaluate agent-generated demand solely based on sales volume. The decisive factor is the remaining contribution margin after all channel-related costs.
A simple model calculation shows the magnitude of the advertising risk
The potential impact on Amazon's advertising can be illustrated with a purely hypothetical example. The historical benchmark is approximately $68.6 billion in advertising revenue in 2025. Let's assume that one-tenth of this revenue base is economically linked to purchasing situations that could be handled through external agents in the future. Furthermore, assuming that only half of this revenue could not be offset by other forms of advertising or additional transactions, this would result in a calculated revenue risk of approximately $3.4 billion. The initial figure has been reported; the percentages are purely scenario assumptions.
This calculation is not a forecast. In particular, it does not assume that ten percent of customers are already churning or that every automated order halves advertising revenue. Its purpose is to illustrate the sensitivity of a large revenue pool to relatively limited changes in behavior.
Similarly, potential losses in advertising revenue do not directly translate into an equally large decline in profit. Costs, new revenue streams, and changes in trading volume would also need to be considered. Furthermore, Amazon does not report a separate operating profit margin for its advertising services.
The crucial insight, therefore, is not that a specific billion-dollar sum will be lost. It is that even moderate shifts in the customer interface can be economically significant. At the same time, adjustments to the business model can mitigate or partially offset such effects.
Current growth figures do not yet prove the Muse effect
Amazon's advertising revenue rose by approximately 11 percent year-over-year to $19.6 billion in the third quarter of 2026. Adjusted for currency fluctuations, growth was 12 percent. This represents continued growth, albeit at a slower pace than in several previous quarters. Amazon attributed this to timing factors, particularly related to Prime Day, and anticipates stronger growth in the fourth quarter.
It would be methodologically flawed to attribute this slowdown solely to the appearance of external AI agents. Temporal proximity is not proof of causation. Seasonal effects, comparison bases, advertising budgets, and changes in the product range can also play a role.
Furthermore, a newly launched product can initially only influence a limited portion of overall purchasing behavior. Even rapid user growth does not immediately translate into a measurable, company-wide effect.
A reliable analysis would require more detailed data: How many product searches begin outside of Amazon? What percentage of these searches still result in an order on the platform? How do advertising contacts and advertising revenue change within comparable customer groups?
The distinction between structural risk and damage that has already occurred is crucial. Muse can be strategically important without demonstrably explaining current advertising growth. A dispassionate assessment must allow for both statements simultaneously.
Meta also needs to earn enough to cover the costs of his assistant
A successful purchasing agent is not automatically a profitable business model. Processing complex requirements, repeated product research, price monitoring, and order fulfillment incur ongoing costs.
An agent who reviews multiple offers, answers questions, and updates their results needs more than a simple static product list. Additional costs include security, payment integration, and customer service.
Meta must therefore decide how to finance these services. Possible options include paid add-ons, referral fees, advertising, or integration into other business relationships. Which combination will ultimately prevail remains to be seen.
Each model creates different incentives. User-paid assistance could be more easily positioned as an independent service, but it must generate sufficient willingness to pay. A commission-based model may initially appear cheaper for consumers, but it creates potential conflicts in the choice of service provider.
A large reach helps distribute fixed development costs, but it doesn't solve every problem. If intensive users generate particularly high ongoing costs while generating little revenue, growth can increase the financial burden.
The crucial question, therefore, is not just whether Meta can attract customers to try it out. It's about whether reliable assistance can be combined with financing that doesn't undermine trust in recommendations.
Standards determine whether openness actually works
Sustainable agent-based commerce requires clear rules for cooperation between users, assistants, merchants, and payment providers. A technically accessible website alone is not sufficient.
A merchant should be able to identify that an agent is acting and understand their authority. The user must be able to specify whether the assistant is only authorized to conduct research, prepare a shopping cart, or finalize an order.
A tiered system of authorization would be beneficial. For example, an agent could independently reorder consumables up to a specified amount, while larger purchases would require approval. Time limits and authorizations that can be revoked at any time would further improve control.
Documentation is equally important. If an order fails, it must be traceable what specifications existed, what information was available, and what action was taken.
The question of liability remains central. An error can originate from the user order, the product labeling, an incorrect conclusion drawn by the agent, or the technical processing. Without clear responsibilities, disputes threaten to erode trust and cost advantages. The fact that the payment industry and commerce are increasingly discussing these issues demonstrates how closely technological development is linked to legal and economic infrastructure.
For brands, the work begins before the next advertising budget
Companies should not interpret this development as an immediate retreat from traditional retail advertising, nor as an uncritical investment in every new AI feature. A more appropriate approach is a gradual adjustment of sales fundamentals.
The first step is to review your own product information. Are the product variants clearly described? Do prices and availability match across different channels? Are the delivery terms understandable? Can quality promises be verified?
The next step is the economic evaluation of individual distribution channels. Agents can provide additional reach, but they can also create fees, price pressure, and new dependencies. Growing revenue is only a success if the quality of earnings remains adequate.
At the same time, brands should differentiate which products benefit most from automated advice. Products requiring extensive compatibility or explanation can gain an advantage if an assistant clearly relates their benefits to specific needs. Weak or contradictory documentation can reverse this effect.
The most robust long-term position arises from a combination of compelling products, reliable data, dependable processing, and multiple customer access points. Those who rely solely on the preferential placement of a single intermediary remain vulnerable – regardless of whether that intermediary is a marketplace or an AI agent.
Three possible market orders instead of one inevitable winner
One plausible development is the controlled opening of large platforms. Amazon could allow selected external agents under defined security and business conditions. This would enable additional demand without completely relinquishing control.
A second possibility is a more isolated landscape. Large retailers and technology companies each operate their own assistants and favor their respective partners. Consumers gain convenient features but still have to choose between ecosystems. Comprehensive, neutral market comparisons would remain limited.
A third development would be the dominance of a few multi-retailer agents. These would consolidate many purchasing decisions and increasingly put affiliated retailers under competitive pressure. This could reduce search costs and improve selection, but at the same time create new intermediary fees and dependencies.
Initially, a coexistence of these models seems the most plausible approach. Repeat purchases can be organized differently than high-value acquisitions. A familiar retailer can be convincing for routine orders, while a multi-agent is more attractive for complex comparisons.
Amazon's position, therefore, doesn't necessarily have to remain unchanged or collapse completely. The company could lose some of its current control while simultaneously gaining additional customers through its own assistance features. Similarly, Meta can establish an important new interface without being able to replace the trading and logistics services of established providers.
In the future, the decisive power will lie between wish and order
The conflict between Meta and Amazon reveals a fundamental shift: The most valuable position in online retail could focus more on the moment when a general need becomes a specific product selection.
Amazon remains well-positioned thanks to its combination of product range, infrastructure, customer relationships, and in-house AI development. However, Muse demonstrates that the initial steps in the shopping experience don't have to be permanently tied to the surface of a single marketplace.
For consumers, potential benefits include lower search costs, better-informed decisions, and less effort. However, these benefits only materialize if recommendations are reliable and commercial interests do not covertly influence the selection.
For retailers and brands, the demands on data quality, differentiation, and cost-effectiveness are increasing. Visibility is not becoming irrelevant. It may simply be achieved less frequently through a visible advertising space and more frequently through inclusion in an algorithmically generated pre-selection.
The rationale, therefore, is that AI agents will likely not simply eliminate intermediaries from online commerce. Rather, they could create a new level of intermediary. The economic winner would then not necessarily be the provider with the largest inventory or the loudest advertising campaign, but the one to whom customers permanently entrust their purchasing decisions. Whether this results in more competition or merely a new concentration of power depends on how open, verifiable, and interchangeable this new interface is designed.
📈🚀 From visibility to trust 👀🤝 Your scalable path with Xpert.Digital

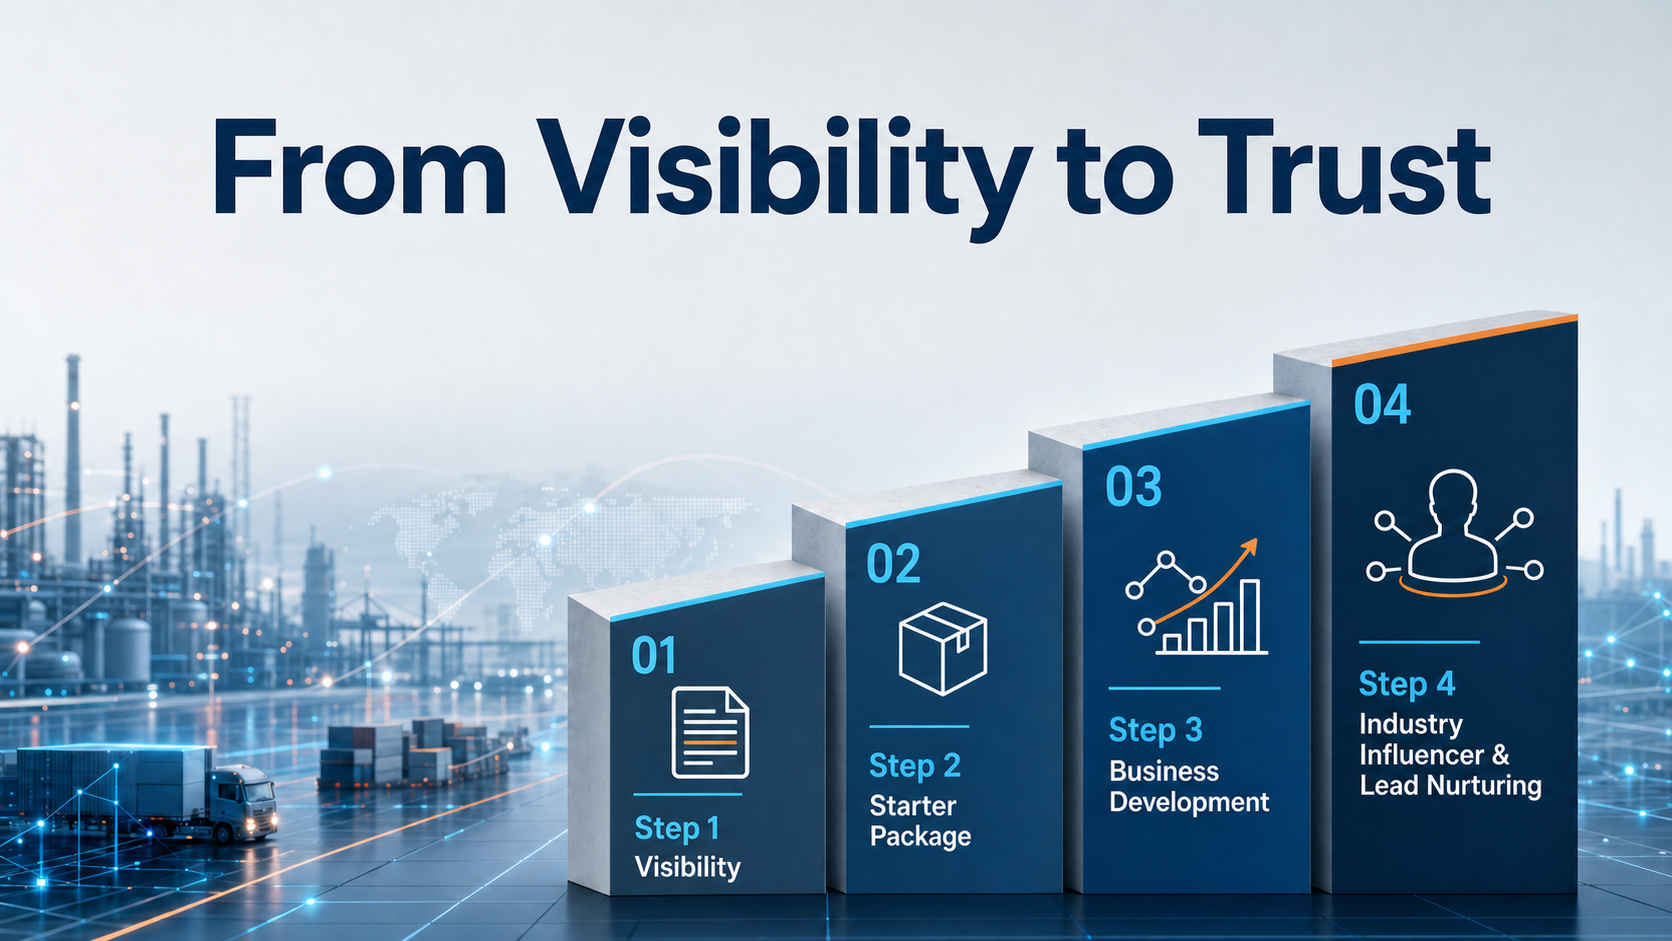
From visibility to trust: Your scalable path with Xpert.Digital - Image: Xpert.Digital
In industrial B2B, sustainable business relationships rarely emerge overnight. They develop step by step – through visibility, professional relevance, recurring touchpoints, and growing trust. Xpert.Digital's 4-stage model addresses precisely this: It offers a structured path that begins with a manageable entry point and can evolve into deeper collaboration in business development if needed.
Instead of relying on loud marketing promises, this model puts the relationship at the forefront. Companies start with clearly defined, easily calculable measures and then decide, based on their own experience, how far they want to expand the collaboration. A key factor for this undisturbed trust-building process: The platform completely avoids annoying advertising ads, so the editorial focus remains solely on the companies' expertise.
More information here:
Your global marketing and business development partner
☑️ Our business language is English or German
☑️ NEW: Correspondence in your native language!

Konrad Wolfenstein
I and my team are happy to be available to you as your personal advisor.
You can contact me by filling out the contact form here wolfenstein@xpert.digital:or simply call me at +49 7348 4088 965. My email address is
I'm looking forward to our joint project.