Why companies are reaching fewer and fewer visitors via Google search – AI is the most convenient scapegoat – Creative image on the topic, with AI: Xpert.Digital
Organic traffic is declining: This is the real reason behind it
AI, ads, new rankings: Why websites are fighting for visibility
Fewer clicks, more competition: How search is changing
Fewer visitors from organic search, more competition from ads, and new ways to find information: For many websites, the foundation of their digital reach is currently changing. But artificial intelligence alone doesn't explain the decline. Changes in search results, ranking losses, and platforms that increasingly provide answers directly within their own interfaces also influence whether users even click on a website anymore. Data from the US and France shows how much organic and paid traffic are diverging – and why publishers in particular are under pressure. At the same time, chatbot referrals currently represent only a small portion of website traffic, but they can still change how people search for information. Therefore, the crucial question is not only how many visitors companies are losing, but also where attention will be generated in the future and how to derive economic value from it.
The new search economy: Why organic traffic is losing ground and digital visibility is becoming more expensive
AI is the easiest scapegoat – but the real battle for distribution is taking place on the platforms
The decline in organic website visits cannot be attributed to a single cause. Artificial intelligence is changing how we search for information, answering questions without requiring a subsequent website visit and shifting attention to closed user interfaces. At the same time, advertisements are taking up more space, search engines are changing their rankings, and certain business models are coming under more pressure than others. Those who attribute all losses to AI are mistaking a visible technological shift for a complete economic explanation.
The figures nevertheless reveal a clear shift. In the analyzed website data, organic visits in the US in August 2026 were 13.2 percent lower than in August 2024. In France, the decline was 24.4 percent. During the same period, visits via paid search increased by 21 percent in the US and by 17.3 percent in France. Organic reach is shrinking, while paid reach is growing. This opposing trend is more economically significant for companies than the isolated question of how many users are now using a chatbot.
However, these figures do not yet explain which factors caused the decline. They initially describe changes within the samples studied. A reliable analysis must therefore distinguish between observation and explanation, between reach and value creation, and between short-term adjustments and structural shifts.
The central perspective is this: The economic value of digital demand doesn't necessarily disappear when fewer people click on websites. However, it is distributed differently. Platforms can retain a larger share of attention within their own offerings, advertising space gains in importance, and companies must compete more intensely to even be perceived as a relevant source of information or a supplier.
Declining visitor numbers do not automatically mean declining demand
An organic website visit only occurs at the end of a multi-stage decision-making process. A person has a need for information, chooses a search channel, receives a display of results, and then decides whether further clicking is worthwhile. Changes at any of these points can lead to fewer visits to a website.
Therefore, a decline in traffic does not necessarily equate to a corresponding decrease in interest in a topic or product. Users may still be searching for the same information, but may already be finding their answers on the search results page or within a chatbot. Similarly, demand may remain high while other websites rank higher or ads capture a larger share of attention.
For companies, this distinction is fundamental. If actual demand falls, the product range, positioning, or target market may need to be reviewed. If, on the other hand, demand remains constant and only access to it changes, the problem is more likely to lie in visibility, channel dependency, and the design of the customer journey to the purchase decision.
The observed trends suggest that several of these processes need to be considered simultaneously. Organic visits are declining, paid visits are increasing, and AI systems currently generate relatively little direct redirect traffic. This doesn't result in a simple substitution pattern where every lost Google click reappears as a new ChatGPT click.
Rather, the relationship between information consumption and website visits is changing. Therefore, for economic evaluation, it is no longer sufficient to simply consider the number of incoming sessions. What matters is what function these sessions previously fulfilled and whether that function has since been taken over elsewhere.
Why averages obscure the actual market shift
Around two-thirds of the websites surveyed lost organic traffic. This shows that the decline is not limited to a few isolated problem cases. At the same time, a significant portion of the absolute losses is concentrated on a small group of particularly hard-hit sites.
In the US, roughly 40 percent of lost visits were attributable to just one percent of websites. In France, this one percent accounted for almost half of the total loss. The decline is thus widespread, but highly concentrated in terms of its absolute magnitude.
These two statements are not contradictory. Many smaller websites may experience moderate losses, while a few large sites lose a significant number of visitors. This is relevant to public perception: Big losers dominate the debate, even though their performance doesn't necessarily reflect the typical experience of an average company.
The differences between the US and France should not be hastily interpreted as evidence of a single national influencing factor. Different industry shares, initial sizes, and the composition of the websites analyzed could influence the results. Without comparable detailed data, it is impossible to definitively determine why the decline in France is significantly more pronounced.
This leads to a clear requirement for corporate management: A general market average is a warning signal, but not yet a suitable individual target value. A specialized industrial supplier, a news portal, and a consumer-oriented advice service face different risks. Their development must be assessed within the context of comparable business models and search intent.
The particular problem for publishers is their relationship between information and revenue
Publishers were particularly hard hit. Their organic visits declined by around 42 percent in both countries. Excluding publishers, the decrease in the US was 7.8 percent. This demonstrates how significantly a single provider group can influence the overall picture.
The difference is economically plausible: For information-driven offerings, the visit itself is often a crucial prerequisite for monetization. Only when people access the website can advertising, subscriptions, or other offers become effective. If the essential informational value is conveyed outside the website, the editorial content can still be utilized without the original provider receiving a corresponding visit.
This doesn't mean that every lost visit causes the same economic damage. A quick visit to answer a simple general knowledge question might be less valuable than the repeated use of a specialized, expert-level resource. Nevertheless, significant losses in reach can strain finances if a business model relies on high traffic.
For transaction-oriented companies, the situation is somewhat different. A manufacturer can more easily absorb a decline in general advice-related visits if qualified product inquiries and sales remain stable. A publisher, whose product is precisely information, does not have this same diversification option to the same extent.
The crucial dividing line, therefore, does not lie solely between large and small websites. It also lies between offerings where information paves the way for a later transaction and those where the use of information itself forms the economic basis.
More advertising changes the competition even without artificial intelligence
The simultaneous increase in paid search visits deserves special attention. In the US, these visits rose by 21 percent within the two-year period under review, and in France by 17.3 percent. While this doesn't directly reflect the extent of increases in advertising budgets or click prices, the figures do show that paid and organic traffic are developing differently.
In addition, the search results display has changed. Since June, according to the observations, the average organic result on desktop has only been visible after scrolling. The ad units have roughly doubled in size. This not only shifts the ranking of individual results but also the distribution of the initially visible screen area.
An organic result can maintain its position among the unpaid search results while still losing actual visibility. Ultimately, economic impact isn't solely determined by whether a website ranks third or fifth. Crucially, it also depends on how many other elements users see beforehand and whether they even reach that result.
This makes interpreting traditional ranking reports more difficult. Stable positions can occur alongside declining click-through rates, even if the content itself hasn't deteriorated. The competition then takes place not only between websites, but also between different presentation formats on the same platform.
This creates additional cost and adaptation pressure for companies. Those who want to compensate for lost organic reach with advertising must assess whether the additional customers gained justify the effort. More paid traffic, in itself, does not guarantee economic success.
Ranking losses and AI effects must be examined separately
Besides changes to user interfaces and search habits, algorithmic changes are also a possible cause. One example cited is a Google update in January 2026, which caused some websites to lose numerous rankings. Such changes can significantly impact the traffic to individual sites.
For a reliable diagnosis, at least three levels must therefore be distinguished. A website may receive fewer visits because it appears less frequently in search results. It may receive fewer clicks while maintaining the same visibility. Or the underlying search volume may decline because users are now asking their questions elsewhere.
These developments can occur simultaneously and reinforce each other. A drop in ranking reduces visibility. Larger ad placements further reduce attention to the remaining organic search results. Finally, AI responses can satisfy some of the information needs before another click is required.
The available total data does not allow for a reliable calculation of the contribution of these factors. Therefore, providing a precise percentage indicating what portion of the decline is solely attributable to AI would not be justified.
In practice, this uncertainty is no reason for inaction. Rather, it calls for a differentiated root cause analysis. Changes should be examined according to page type, search intent, device, time period, and economic significance. Only in this way can companies avoid reacting to a ranking problem with an AI strategy or attempting to solve fundamentally changed search behavior solely through technical search engine optimization.
Chatbots are changing information channels more than their visitor numbers suggest
Visits via ChatGPT and other chatbots have so far accounted for only about 0.5 percent of all visits. This small share might give the impression that AI hardly plays a role in the actual distribution of demand. However, such a conclusion would be too narrow.
Direct redirection to websites only measures usage that ends with a click. If a chatbot has already answered the question sufficiently, no measurable visit to the original information source occurs. A successful answer can therefore result in no contact being visible in the website analytics at all.
US desktop data illustrates this difference. With ChatGPT, only 5.2 percent of conversations resulted in a website click. In contrast, with Google, 31.1 percent of search queries triggered a click. However, these two figures are based on different units of usage: a conversation is not the same as a single search query. Therefore, they should not be considered a completely comparable measure of efficiency.
Nevertheless, they point to a fundamental difference in product logic. Traditional search functions as an intermediary between information needs and external offerings. A chatbot, on the other hand, focuses more on fulfilling information needs directly within its own interface.
For companies, this means that a small percentage of AI-generated referrals can still play a significant role in the decision-making process. Similarly, a brand can lose importance without this loss being immediately reflected in a decline in a previously large AI traffic stream.
Less traditional searches can gradually develop into a structural risk
Further insights are provided by the data from households with access to ChatGPT Search. These households subsequently searched on Google, Bing, and Yahoo an average of 9.4 percent less frequently. After 20 weeks, the decrease had reached 17 percent.
Within the studied group, this suggests that usage was not limited to a one-off test. The more pronounced decline after several weeks is consistent with a gradual change in habits. Users may learn to rely directly on the chatbot for certain tasks.
However, these results should not be generalized to all internet users without further scrutiny. Access, study design, and household composition can influence the observed trends. It also remains unclear which search queries declined most sharply and whether certain types of searches remained largely unchanged.
From an economic perspective, this distinction is crucial. If primarily simple informational questions are migrating to chatbots, this affects different content than a shift towards purchase-oriented product research. The number of lost searches alone does not indicate how much economically relevant demand is affected.
The strategic consequence, therefore, is not to prematurely dismiss traditional search engines. Rather, companies should observe for which tasks their target groups use other information channels and in which cases a visit to their own website remains necessary or desirable.
🎯🎯🎯 Data-driven B2B industry hub as a quasi-in-house solution


The quasi-in-house solution: How Xpert.Digital closes operational gaps in B2B marketing and sales – Smart Content-Driven Business - Image: Xpert.Digital
Xpert.Digital is a data-driven B2B industry hub led by Konrad Wolfenstein . The company acts as an external, quasi-in-house solution for industrial partners, closing operational gaps in marketing, content, and sales – without requiring additional resources on the client side.
More information here:
What well-structured content can achieve – and what has not been proven
Higher conversion rates do not make a small channel a replacement
ChatGPT visitors converted more frequently than Google visitors in the data analyzed. This is an interesting quality signal, but it must be evaluated in conjunction with the actual volume.
For 55 websites with conversion tracking, Google was credited with 964 conversions. All AI chatbots combined accounted for 36. This means that in this sample, Google delivered almost 27 times as many recorded conversions as all the AI chatbots combined. A relatively powerful, small channel was therefore still far from replacing the absolute contribution of traditional search results.
Furthermore, it is not specified whether all recorded conversions had the same economic value. A newsletter signup, a contact request, and a completed purchase cannot simply be equated. Therefore, additional information on revenue, margin, and conversion quality would be required for a complete evaluation.
One possible explanation for higher conversion rates lies in more thorough pre-qualification. Someone who has had a detailed dialogue with a chatbot and then specifically visits a website might already have more concrete requirements. The click would then be a later step within a longer decision-making process.
This explanation, however, remains an interpretation. The numbers alone prove neither why users convert more frequently, nor whether the advantage persists with larger volumes. For companies, the sensible conclusion is therefore: AI referrals should be taken seriously, but not confused with an already proven ability to fully compensate for lost search visits.
When brand impact no longer fully appears in web analytics
Dialogue-based information systems create a larger gap between actual influence and measurable website contact. A brand can be mentioned, compared, or excluded in a response without a subsequent visit.
This changes the significance of web analytics. While it remains important for evaluating visits and conversions, it may now represent a smaller part of the preceding information-gathering phase. The measurable entry point may be later than the first relevant contact with the company.
This does not mean that every mention is economically valuable. A mention can be casual, inappropriate, or critical. Even a frequently cited website does not automatically generate more demand. Several independent steps lie between visibility, perceived competence, the selection decision, and revenue.
A meaningful evaluation should therefore not only consider whether a brand is mentioned. It should also examine in which questions it appears, what attributes are ascribed to it, and whether its offerings are described accurately. Especially in the B2B sector, incorrect information about technical capabilities or areas of application can be more relevant than simply a low frequency of mentions.
The challenge lies in systematically recording such observations without prematurely deriving seemingly precise key performance indicators. A single chatbot response is not a reliable market indicator. Recurring patterns in economically relevant questions, however, are a worthwhile subject for strategic monitoring.
What well-structured content can achieve – and what has not been proven
A study of German-language websites compared cited pages with uncited pages from the same domain. Pages with several structural features were cited 2.1 times more often than poorly optimized pages. The features considered included a table of contents with anchor links, article markup, and at least five H2 headings.
A table of contents alone was associated with a 1.7 times higher citation frequency. These results suggest that clearly structured content may appear more frequently in AI responses. However, they do not prove that adding a table of contents afterward increases the likelihood of being cited accordingly.
Structured pages may be more comprehensive, better editorially maintained, or more relevant to specific questions. Even within the same domain, pages can differ significantly in quality, topic, and timeliness. Such factors can explain part of the correlation.
The practical conclusion is still valid: content should be structured logically and individual questions should be answered clearly. Meaningful subheadings help to distinguish between different sections. Appropriate technical markup can provide additional information about the content type.
However, this should not become a mechanical optimization formula. Five headings are no proof of quality, and an artificially lengthened table of contents does not replace substantive content. Economic benefit does not arise from fulfilling a formal checklist, but from clear, reliable information that is relevant to the target audience.
Up-to-dateness is a promise of quality and not merely an add-on to the title
Including a current year in the title was associated with a 2.7 times higher citation frequency. This finding is expressly preliminary and should therefore neither be ignored nor treated as a definitive guideline.
For time-sensitive topics, specifying a year can be useful. It indicates the time period to which a market comparison, price overview, or technical evaluation refers. At the same time, it creates the expectation that the content has actually been reviewed accordingly.
Simply changing the year without any factual update does not improve the quality of information. On the contrary, it can suggest a level of accuracy the article lacks. From a business perspective, this would be a short-term visibility measure with potential long-term costs to trust.
No discernible advantage was found with the llms.txt file either. Of the cited pages, 11.7 percent originated from domains containing such a file. Across all domains examined, the corresponding figure was 14 percent. These values do not demonstrate a positive correlation with citation.
The different reference points – cited pages on the one hand and examined domains on the other – also limit the interpretation. No general negative effect can be derived from the figures. The only reliable finding is that the study provides no convincing evidence of an advantage to this measure.
This is significant for prioritizing scarce resources. Technical quality, clear structure, and actual up-to-dateness should not be overshadowed by technically impressive but insufficiently substantiated individual measures.
Advertising follows attention even in dialogue-based systems
AI-generated responses are simultaneously evolving into an advertising environment. For the same questions studied, 39.9 percent of ChatGPT responses contained an advertisement at the end of October, compared to 36.1 percent at the end of August. This represents an increase of 3.8 percentage points.
The number of different advertisers per question also increased, from an average of 1.82 to 2.14. Approximately half of the responses containing ads involved at least two advertisers. These figures apply to the questions examined and should not be automatically interpreted as the overall advertising rate for all ChatGPT usage.
The stronger advertising presence is noticeable for B2C topics and questions with purchase intent. B2B questions and purely informational questions attracted fewer ads. From a business perspective, this is understandable: Where a concrete purchase decision is more likely, generating attention can be more directly attractive for advertisers.
This creates an important parallel to traditional search. Even in a dialogue-based interface, information delivery and commercial placement can coexist. The form of interaction changes, but the competition for purchase-oriented attention remains.
For companies, the distinction between content-based presence and paid visibility is therefore becoming increasingly important. A factual mention within a response and an advertisement are different forms of contact. Their costs, credibility, and impact should not be lost in a single visibility metric.
International expansion creates different competitive conditions
Google is expanding its AI-powered ads to ten more countries: Australia, Canada, India, Kenya, Malaysia, New Zealand, Nigeria, Pakistan, the Philippines, and Singapore. Brazil, Mexico, and the UK are expected to follow this quarter. Germany is not included in this expansion.
In the US, ads will now also appear in response to follow-up questions and will be marked as "Sponsored." This brings commercial communication closer to an ongoing dialogue. A subsequent question can contain additional requirements, preferences, or restrictions, thus creating a different decision-making context than the original inquiry.
It's too early to determine how effective such placements actually are. Likewise, it's unclear how users will react to the combination of advice and advertising. The expansion initially demonstrates that the commercial use of dialogue-based search interfaces is continuing to develop.
This creates a heterogeneous environment for internationally operating companies. Advertising opportunities, visible formats, and competitive intensity can vary from market to market. Therefore, an approach that works in one country cannot automatically be transferred to all other countries.
Budget planning should also take these differences into account. International presence alone does not justify a consistent investment in new advertising formats. Crucial factors are the availability of the respective formats, the economic significance of the market, and the demonstrable quality of the contacts gained.
Partner content changes access to the visible response
In addition to open web results, prepared partner content also plays a role. An internal channel called "Labrador" is used for recipes, tests, and guides. It comprises twelve providers with a total of 43 domains, including Dotdash Meredith, Hearst, Condé Nast, Axel Springer, Reuters, and AP.
For the pages in question, ready-made summaries are available, which appear before regular web results. This allows for an additional selection and condensation stage between the original publication and the final user response.
This intermediate stage is economically significant. If content is selected and summarized before the actual response process, its potential visibility is determined not only by its general discoverability on the open web, but also by its inclusion in such content channels and the design of the prepared summary.
This does not imply that ordinary websites are categorically excluded. Nor does the description demonstrate that individual publishers have complete control over the responses. However, it does show that information processing is more complex than simply retrieving the best publicly available page.
For companies and publishers, this means another dependency: visibility can depend on several successive selection decisions. Each condensation can highlight certain aspects and omit others. Therefore, those who only look at the original publication may not see which information actually reaches the user later.
Rankings lose their lower positions when they are summarized
The effect of such compression is particularly evident in rankings. In formats like "The ten best...", entries in positions one to three were included in the summary 70 percent of the time. For positions four to six, the proportion was 41 percent, for positions seven to ten it was 23 percent. From position eleven onward, it was only twelve percent.
These values refer to inclusion in the analyzed summaries. They do not represent general probabilities of a company being mentioned anywhere in ChatGPT. Nevertheless, they do show a clear correlation in position.
An existing ranking can be further refined by summarizing the results. A list with numerous alternatives initially conveys a wide range of choices. However, if the condensed version primarily focuses on the top-ranked options, the user is presented with significantly fewer choices.
For companies, this puts the value of simply being listed into perspective. Being represented on a publicly visible comparison site can be helpful. However, if an offer is listed far down the list, it may not be included in a later summary.
The economic significance of a placement thus derives from more than just the reach of the original article. It is also crucial whether the mention persists after further selection and summarization steps. Visibility is, in a sense, filtered multiple times.
However, this does not justify a one-sided pursuit of top positions at any cost. A credible, professionally appropriate assessment remains more valuable than a prominent placement in an unsuitable or questionable environment.
Companies need to differentiate the value of their content more precisely
The developments described argue against a blanket strategy of generating as much organic traffic as possible. Not every visit contributes equally to revenue, customer loyalty, or market position.
For economic management purposes, content should be differentiated according to its function. Some answers simple knowledge questions, others support supplier selection, explain complex services, or facilitate specific contact. A decline in these categories has various consequences.
Especially in the B2B sector, a small number of qualified contacts can be more valuable than a large number of general informational visits. This doesn't mean that early information-gathering phases become unimportant; their contribution simply isn't always immediately reflected in a sale on the same page.
Therefore, a combination of channel, content, and results analysis is advisable. Companies should examine which topics are losing visitors, whether inquiries are declining simultaneously, and whether the quality of remaining contacts is changing. Even a shift from many unspecific to a few specific visits can have a different economic impact than the pure traffic trend might suggest.
Conversely, a stable total number of inquiries should not obscure the fact that a company is increasingly only visible through paid access. In such cases, demand may still be present, but at altered costs and with greater dependence on platforms.
The crucial task is a reliable measurement system, not a new fashion indicator
An appropriate response to change begins with accurate measurement. Organic visits, rankings, ad impressions, AI referrals, and conversions answer different questions. None of these metrics should be used to represent overall business success.
First and foremost, a consistent temporal perspective is crucial. Short-term fluctuations may have different causes than sustained shifts. Technical changes, major content revisions, and identifiable ranking events should also be considered in the interpretation.
Furthermore, a distinction must be made between observed results and presumed causes. If visits decline immediately after a change, this warrants investigation, but does not yet constitute conclusive proof of causation. The same applies to a subsequent increase after an optimization measure.
Additional caution is advised when monitoring AI visibility. Individual responses can vary. Meaningful observation therefore requires recurring, comparable questions and a transparent evaluation of the results. In addition to the mention itself, factual accuracy, thematic relevance, and positioning should be considered.
The goal is not to produce the most comprehensive reporting possible. It's about improving decision-making: Which content warrants further investment? Which declines are economically manageable? Where will additional acquisition costs arise? And which platform dependencies are developing into a significant business risk?
The viable perspective lies beyond the old clickbait promise
The available data does not justify either a statement of complacency or the claim that traditional search engines have already lost their economic significance. In the conversion sample studied, Google still delivered a significantly larger absolute result contribution than all AI chatbots combined. At the same time, the low click-through rates of dialogue-based systems demonstrate why AI does not necessarily translate its influence fully into new website traffic.
The central structural change concerns the distribution of information, attention, and access. Users can learn more without even opening a website. Platforms can keep this information consumption more firmly within their own interfaces. Companies must therefore learn not to equate value creation solely with maximizing organic traffic.
This doesn't devalue high-quality content. However, it does change the conditions under which its production is economically successful. Technical substantive content, a clear structure, and credible timeliness remain important. Added to this are the ability to be accurately represented in diverse information environments and a dispassionate evaluation of the resulting business outcomes.
The clearly reasoned perspective is therefore: AI alone does not threaten organic traffic. The critical factor is the interplay of changing habits, reduced redirects, additional ad space, algorithmic redistribution, and multi-stage content selection. Successful companies will need to understand these mechanisms separately and manage them together.
The scarcest factor in the future will not necessarily be the amount of available information. What will be scarce is reliable access to attention at the crucial moment. Those who assess this access economically, instead of merely defending visitor numbers, can evaluate the change more realistically and respond to it more effectively.
📈🚀 From visibility to trust 👀🤝 Your scalable path with Xpert.Digital

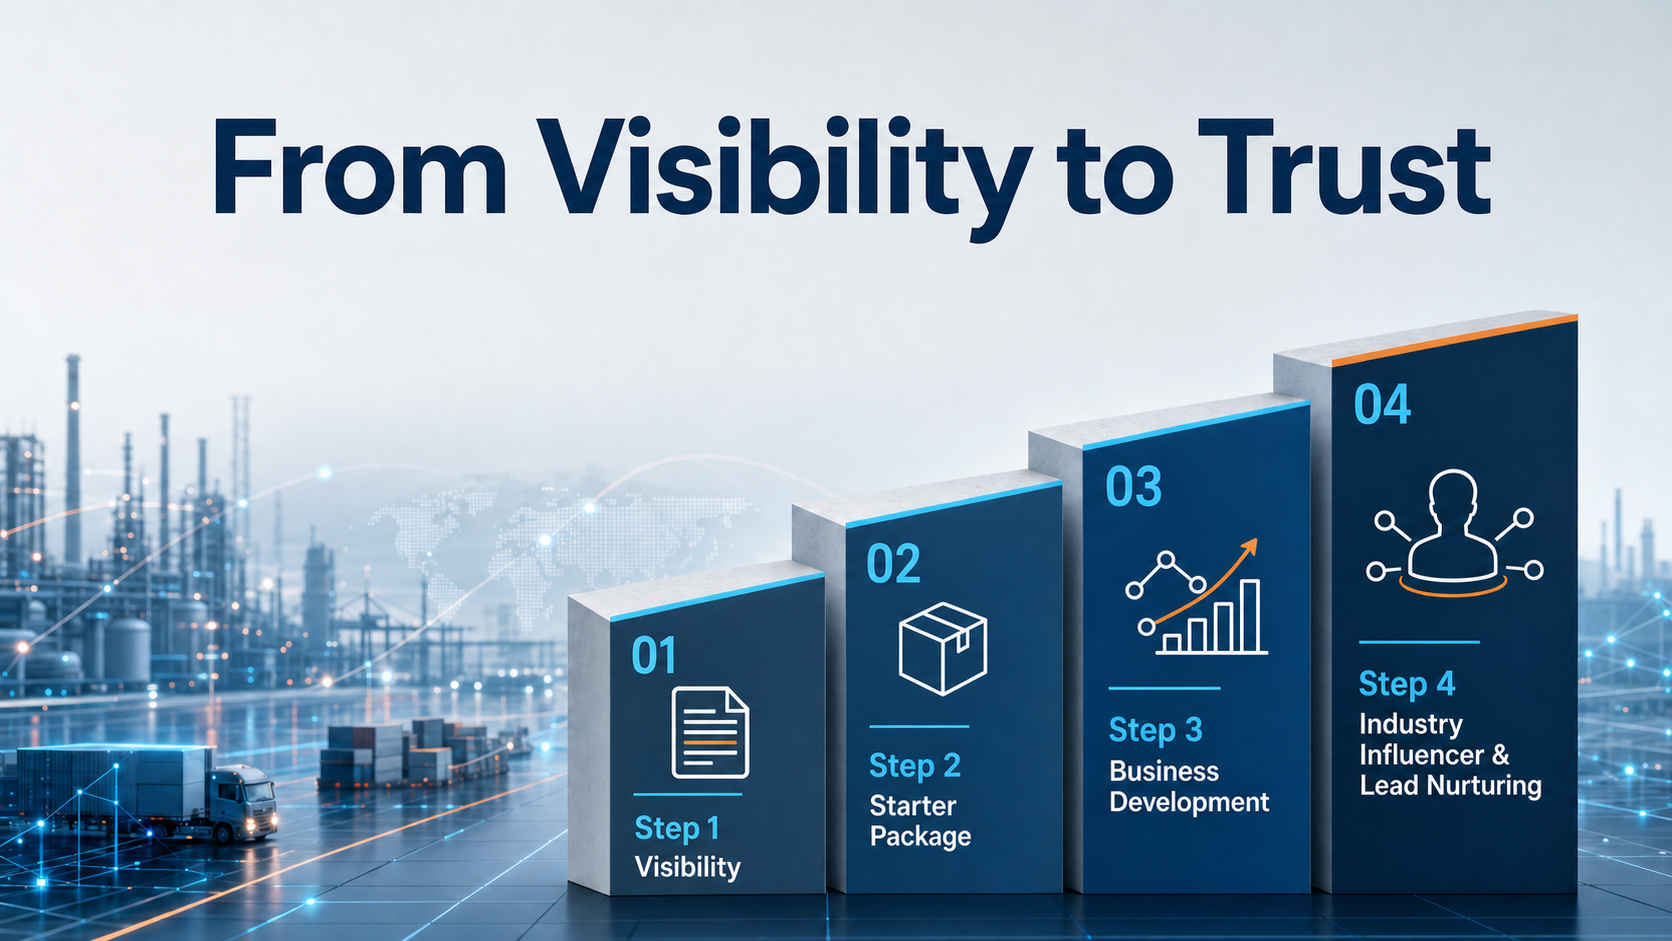
From visibility to trust: Your scalable path with Xpert.Digital - Image: Xpert.Digital
In industrial B2B, sustainable business relationships rarely emerge overnight. They develop step by step – through visibility, professional relevance, recurring touchpoints, and growing trust. Xpert.Digital's 4-stage model addresses precisely this: It offers a structured path that begins with a manageable entry point and can evolve into deeper collaboration in business development if needed.
Instead of relying on loud marketing promises, this model puts the relationship at the forefront. Companies start with clearly defined, easily calculable measures and then decide, based on their own experience, how far they want to expand the collaboration. A key factor for this undisturbed trust-building process: The platform completely avoids annoying advertising ads, so the editorial focus remains solely on the companies' expertise.
More information here:
Your global marketing and business development partner
☑️ Our business language is English or German
☑️ NEW: Correspondence in your native language!

Konrad Wolfenstein
I and my team are happy to be available to you as your personal advisor.
You can contact me by filling out the contact form here wolfenstein@xpert.digital:or simply call me at +49 7348 4088 965. My email address is
I'm looking forward to our joint project.